Browse All Articles

Win the Golden Quarter: 8 Consumer Spending Predictions
The Golden Quarter is stretching out.
The Golden Quarter is no longer defined by a single shopping peak. Cardlytics analysed four years of UK purchase data, and consumer shopping trends point to a longer, steadier shopping season. Easing utility bills have unlocked more flexibility for households, meaning strong consumer resilience is hiding behind a seemingly flat top-line.
−0.8%
Overall tracked spending contracted slightly to £31.8bn — a decrease driven by falling utility costs rather than a lack of consumer confidence.
+1.7%
Excluding utilities, core quarterly spending grew. Discretionary purchasing remained resilient.
65p
For every £1 households saved on essential bills like energy and broadband, 65p was redirected into other sectors.
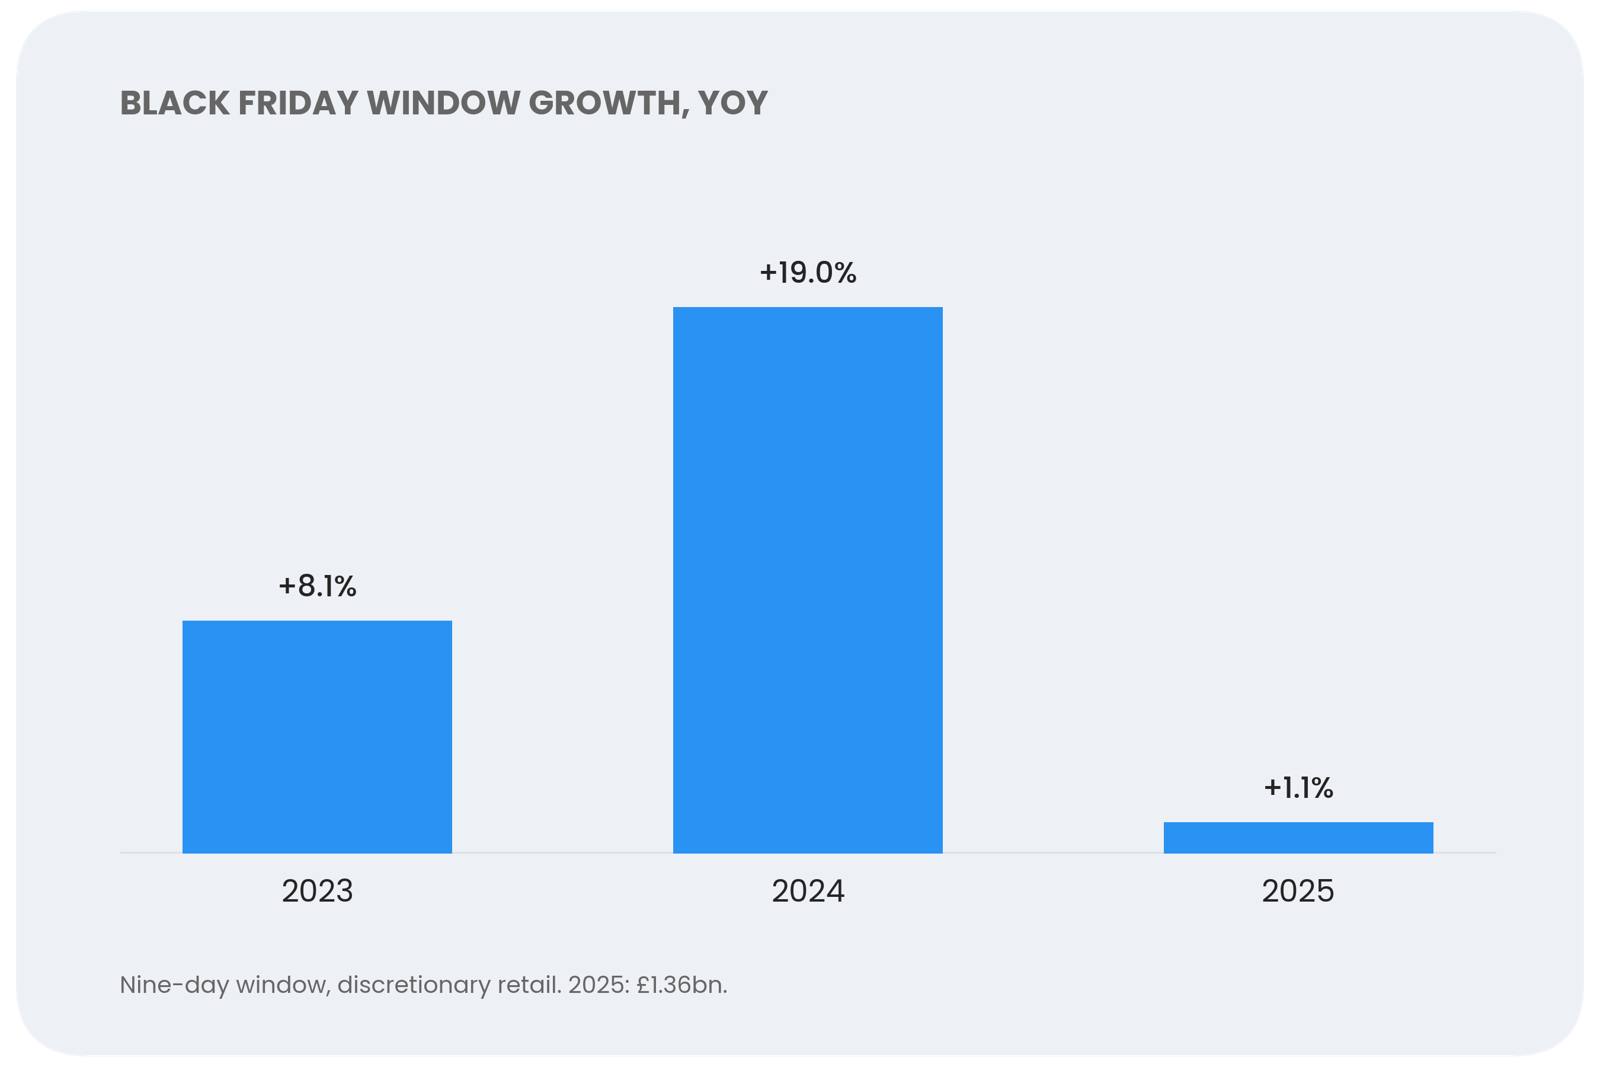
+1.1%
The traditional nine-day Black Friday window saw modest growth, levelling out after the 19% surge the prior year.
Three of our eight predictions
1. Black Friday won't grow: It is now a flat event. Shoppers are spending more in the weeks before it starts.
2. Discounters win Christmas dinner: Discount supermarkets will pass 10% of all grocery spend, hurting the mid-market brands.
3. The party moves to the pub: Sit-down dining is dropping. Pubs will hold steady, while fast food only grows because prices went up.
Get all eight predictions and how to win
The full report covers every prediction, including why retail will take more share, a record quarter for gaming and why next summer gets booked before Christmas, with the data behind each one, its trend rating and what it means for advertisers. Plus the one to watch: will December stall again?
The £2.2bn Switch: where UK spending went in H1 2026 — and where it goes next
UK tracked card spend fell 1.2% year-on-year in the first half of 2026, to £71.5bn — the first decline in our four-year series. Read that as a consumer in retreat, and you’ll misread the entire year. This is not a story of retrenchment. It’s a story of redirection. Households paid £2.2bn less to energy and broadband providers in H1, re-spent 60p of every £1 saved, and banked the remaining 40p. Strip household bills out of the numbers and spending actually rose 2.4%.
The biggest structural shift in our dataset
Utilities’ share of wallet has fallen from 26.4% in 2023 to 20.5% today — a six-point structural handback in three years, and the biggest shift we’ve measured. Energy suppliers alone returned £1,759m to households in H1 2026; broadband switching handed back a further £475m. Where did the money go? Into e-commerce (+£382m), specialty grocery (+£186m), discounter grocers (+£132m), taxis (+£124m), apparel (+£106m) and airlines (+£94m). The result is a changing of the guard: Retail is now the UK’s biggest tracked category at 29.3% of wallet, edging past Grocery’s 28.3%.
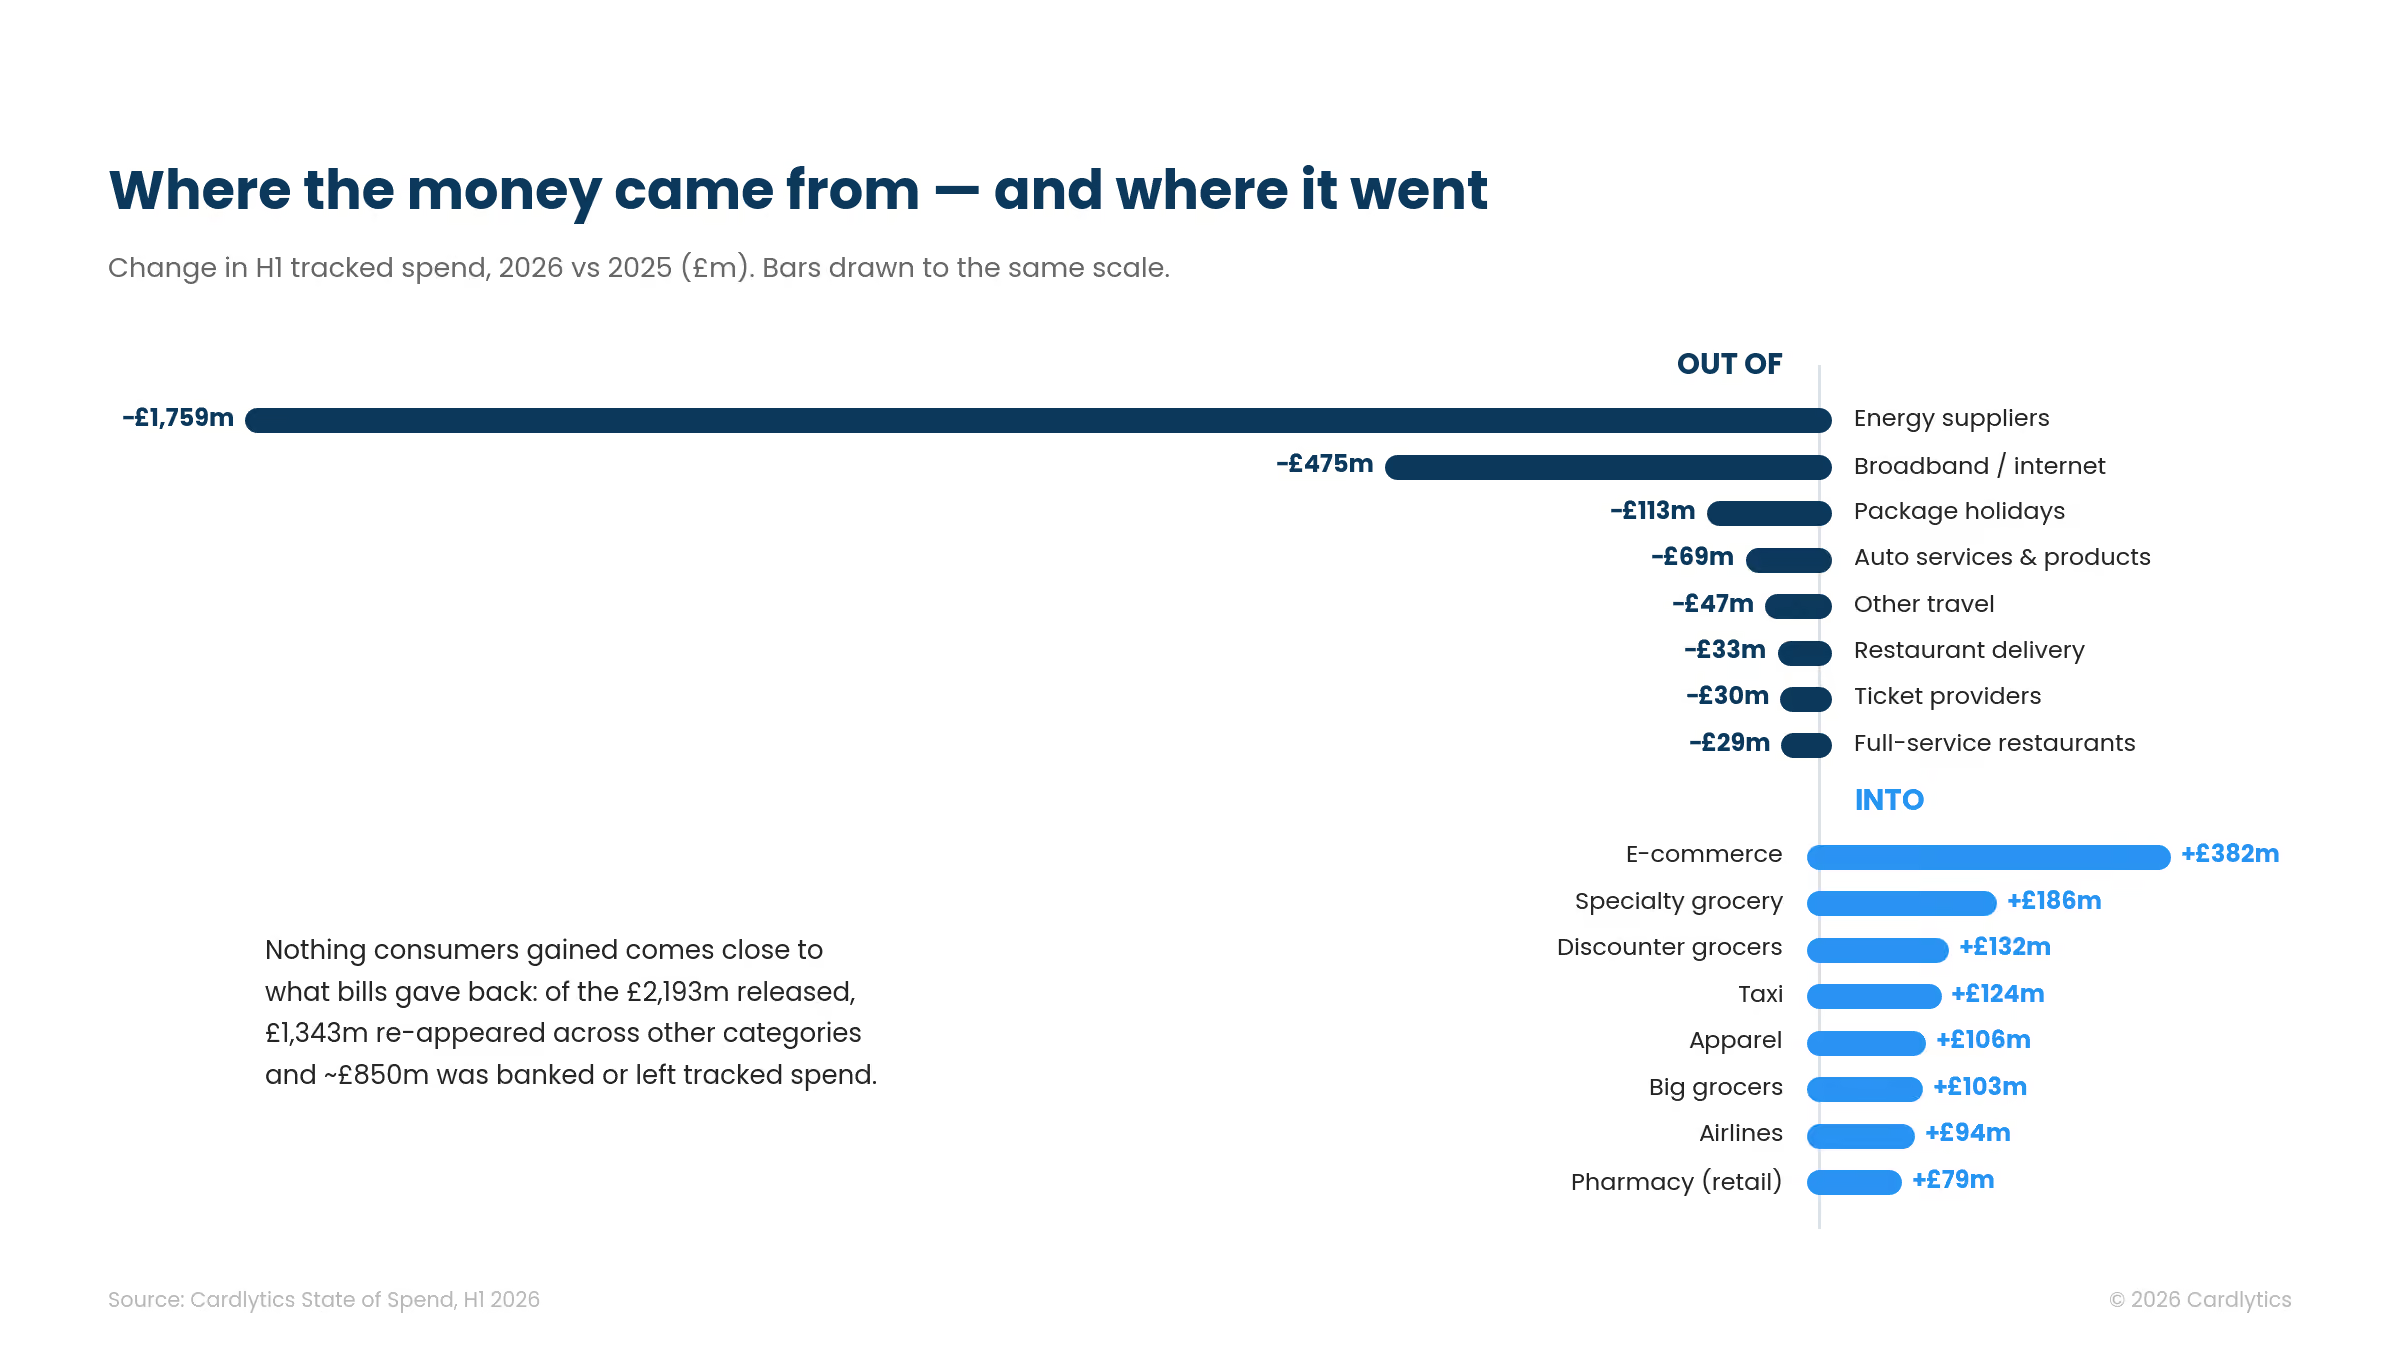
Not every pound found a new home. Of the £2,193m released by bills, £1,343m reappeared across other categories — and roughly £850m left tracked spend altogether, saved or spent beyond the panel.
Value and premium both win. The middle pays for it.
Grocery added £544m (+2.8%), but the growth sits at the two ends of the market. Discounters grew visits 6.4%; high-end grocers grew them 6.9%. Both ends of the barbell are taking trips from the middle: the Big Grocers lost visits (−1.4%) and held spend only through bigger baskets (+2.6% ATV).
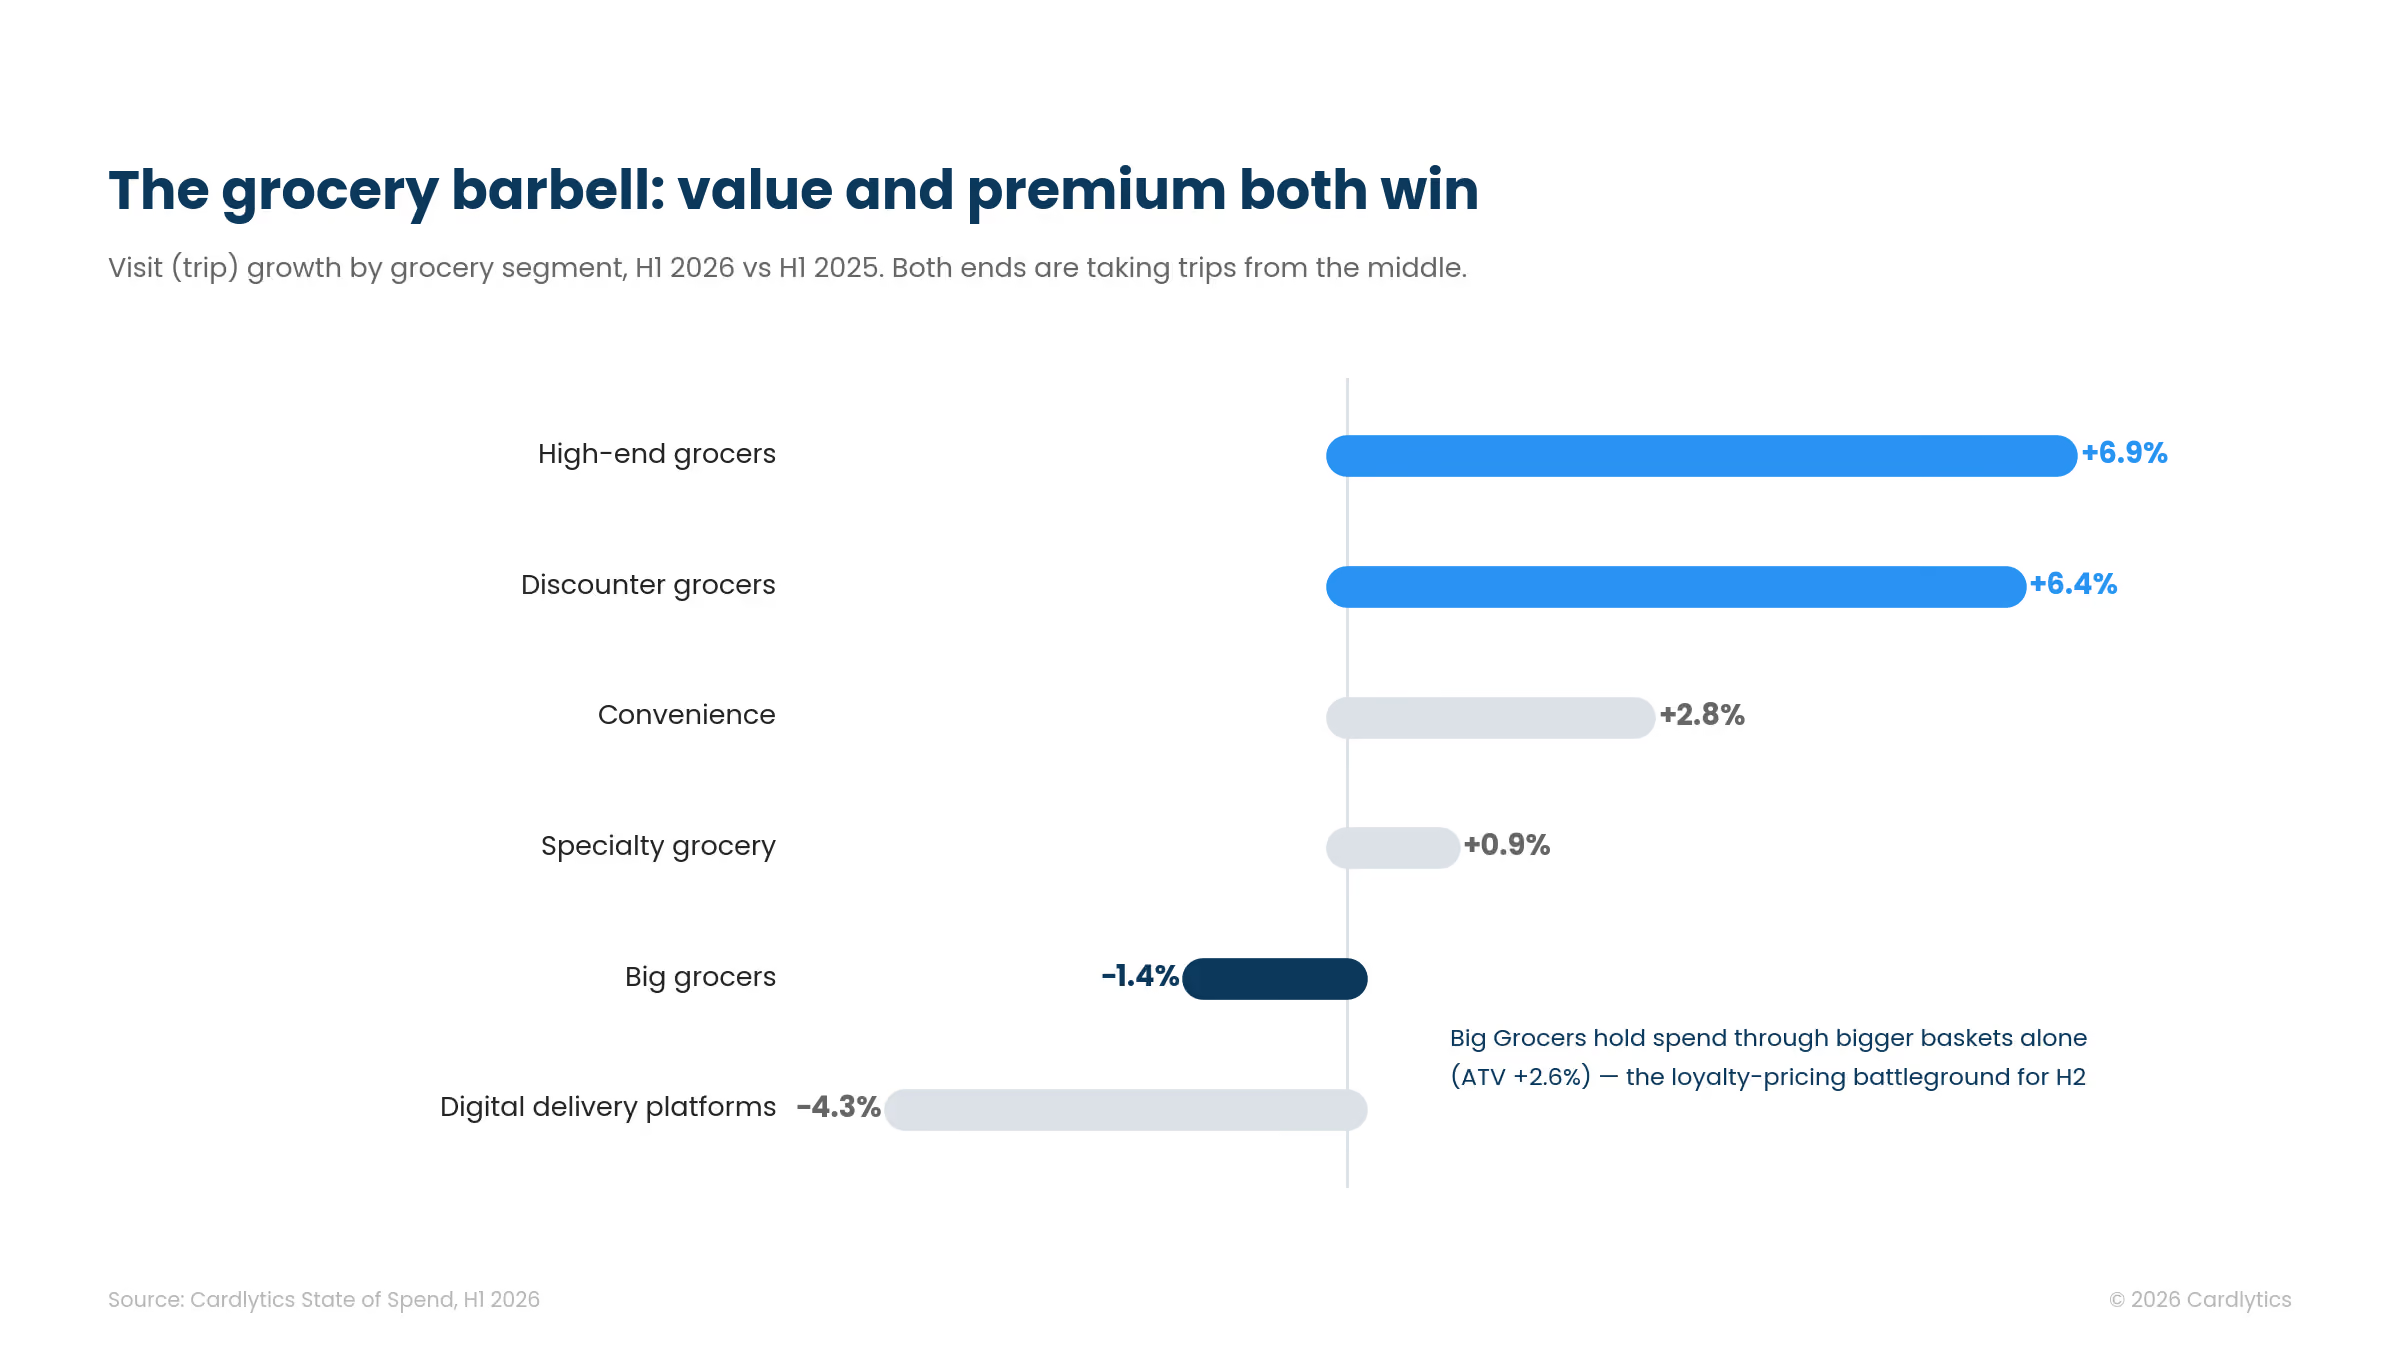
And quiet inflation is back. Grocery basket values rose 1.9% — three times the pace of the two prior years — while meal kits sold through grocers grew 23.8% even as DTC meal-kit subscriptions fell 5.5%
The casualties are mid-priced commitments
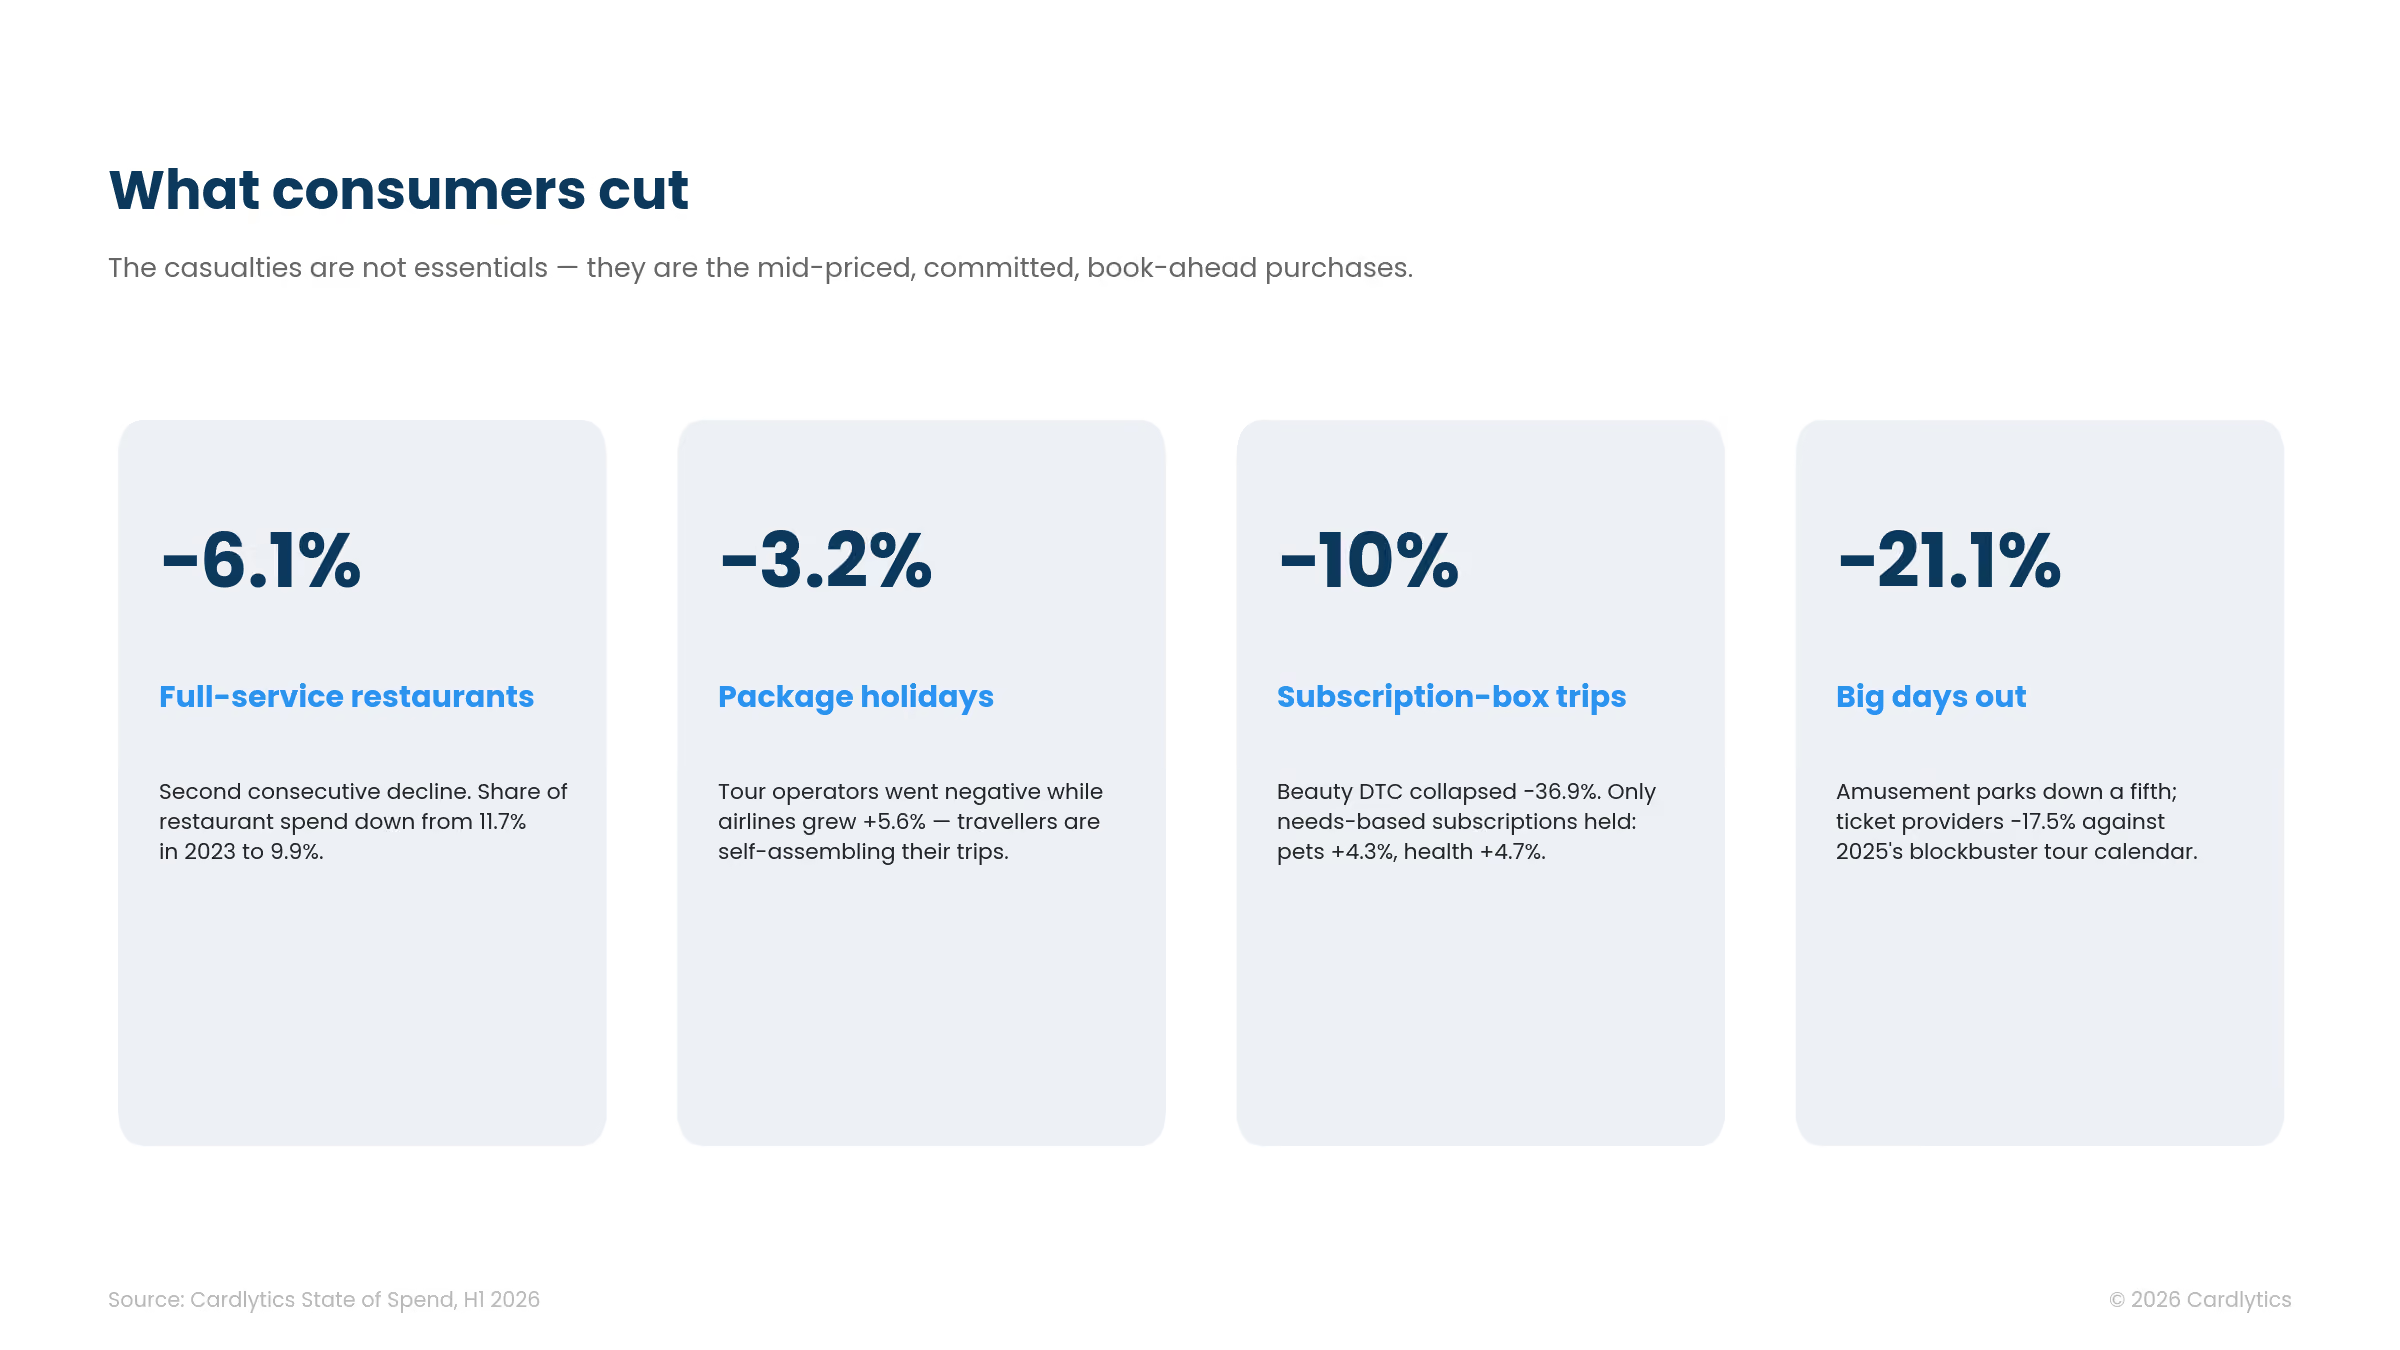
What consumers cut isn’t essentials — it’s the mid-priced, committed, book-ahead purchase: the £30 sit-down meal, the package holiday, the monthly box, the big family day out. Full-service restaurants fell 6.1%, a second consecutive decline that takes their share of restaurant spend from 11.7% in 2023 to 9.9%. Package holidays dropped 3.2% while airlines grew 5.6% — travellers are self-assembling their trips. Subscription-box trips fell 10%, with beauty DTC collapsing 36.9%; only needs-based subscriptions like pets (+4.3%) and health (+4.7%) held. And big days out fell hardest, with amusement parks down 21.1%.
Even the apparent winner looks fragile. Fast food grew 5.3% — but every point of it is price. Trips fell 4.2% while transaction values rose 9.9%. Growth built on charging fewer visitors more is a churn risk, not a success story. Expect an H2 value war.
What H2 looks like
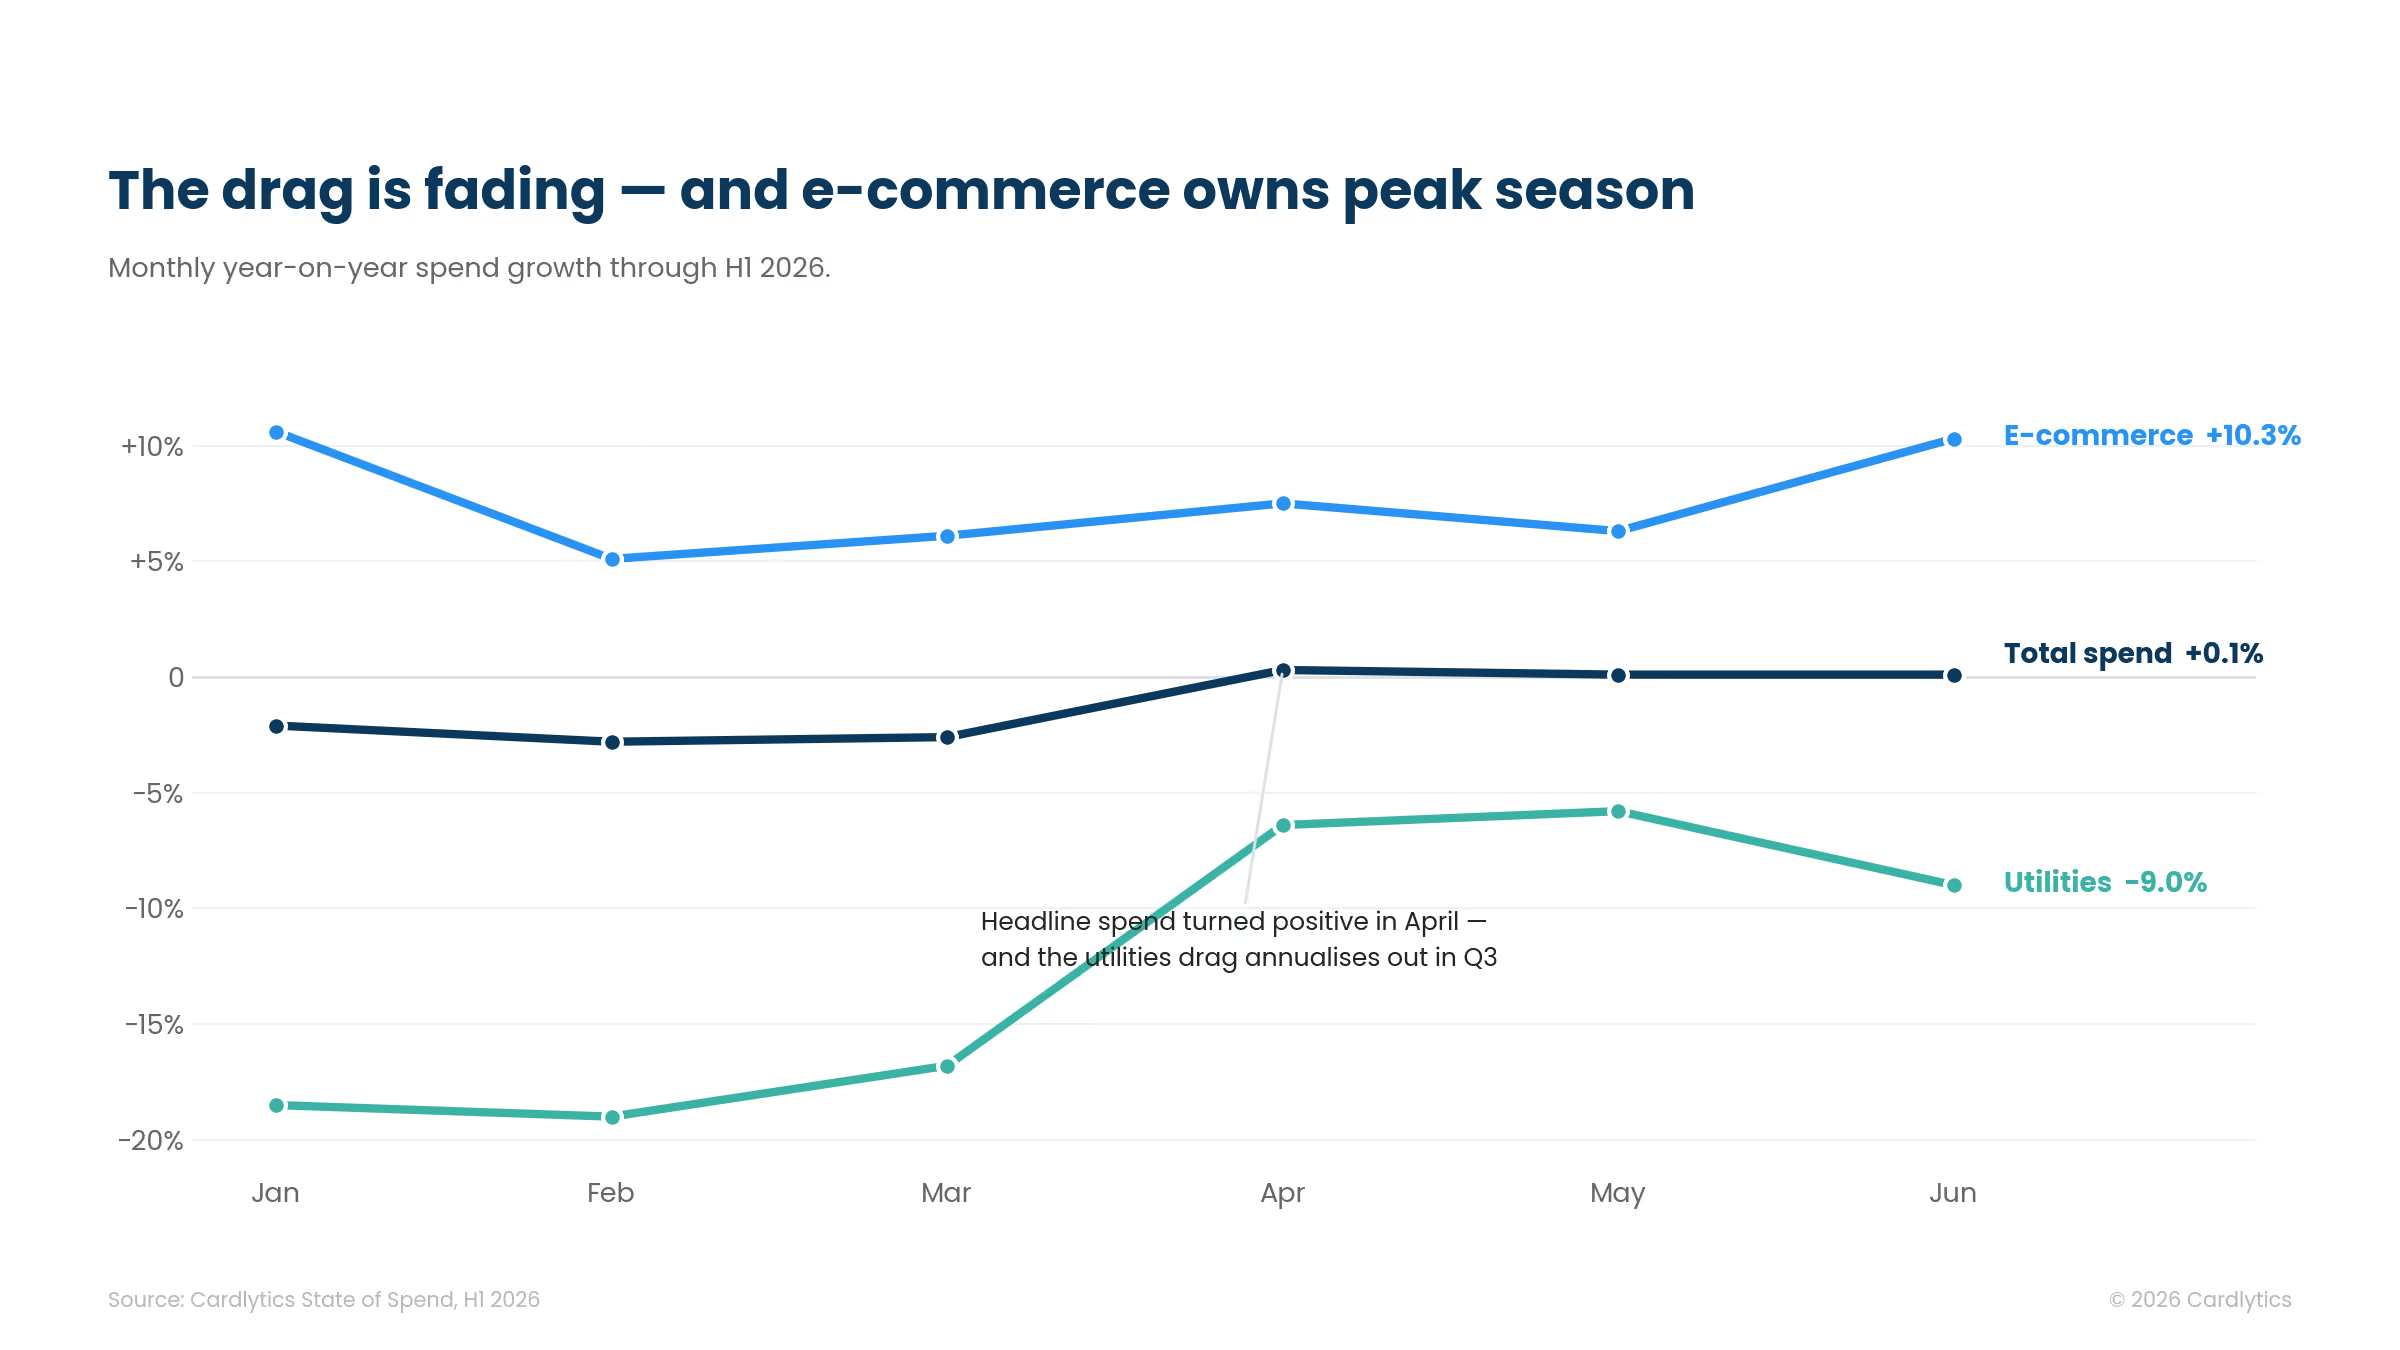
The monthly data points one way. Headline spend turns positive in Q3 as 2025’s energy price cuts annualise out of the comparison. E-commerce — six straight months of acceleration, +10.3% in June — owns peak season from Prime Day through Black Friday to Christmas. Apparel goes negative without intervention, after an eight-point deceleration in six months. The value war spreads from grocery loyalty pricing to QSR discounting. Travel books later and shorter. And pharmacy keeps compounding, growing 65–75% in every month of H1 — on track to roughly double 2024 levels by year-end.
What advertisers should do while the money is in motion
Each shift needs a different brief — and this is precisely where Card-Linked Offers and Cardlytics Insights earn their keep.
Grocers should fight on trips, not baskets: with spend held up by inflation alone, offers must defend visit frequency against both discounters and premium switchers. Retailers should start peak season early — e-commerce momentum says pull Q4 acquisition forward, and apparel brands need conquesting and basket-building before the decline hardens. Restaurants should buy back the lost visit with frequency-based offers that attack the trips problem directly. Travel brands should move offers closer to departure and target lapsed package-holiday spenders with DIY trip components — flights, stays, taxis. Subscription brands should put retention before acquisition: with trips down 10%, churn-saving offers are the priority. And everyone should court the wellness wallet — pharmacy is the fastest-growing high-value audience in our panel, relevant to health, beauty, fitness and grocery advertisers alike. The £2.2bn switch is still in motion. The brands that win H2 will be the ones that meet the money where it’s moving — not where it used to live.
About this data
Findings draw on Cardlytics UK card-spend data across a panel of 2,195 tracked brands, mapped to 8 categories and 58 subcategories. The analysis covers January–June of 2023–2026 on spend, trips and average transaction value (ATV). Year-on-year comparisons are H1 2026 vs H1 2025 unless stated.
The Great UK Travel Rotation
What UK travellers did in the first five months of 2026 — and what the data predicts for the rest of the year.
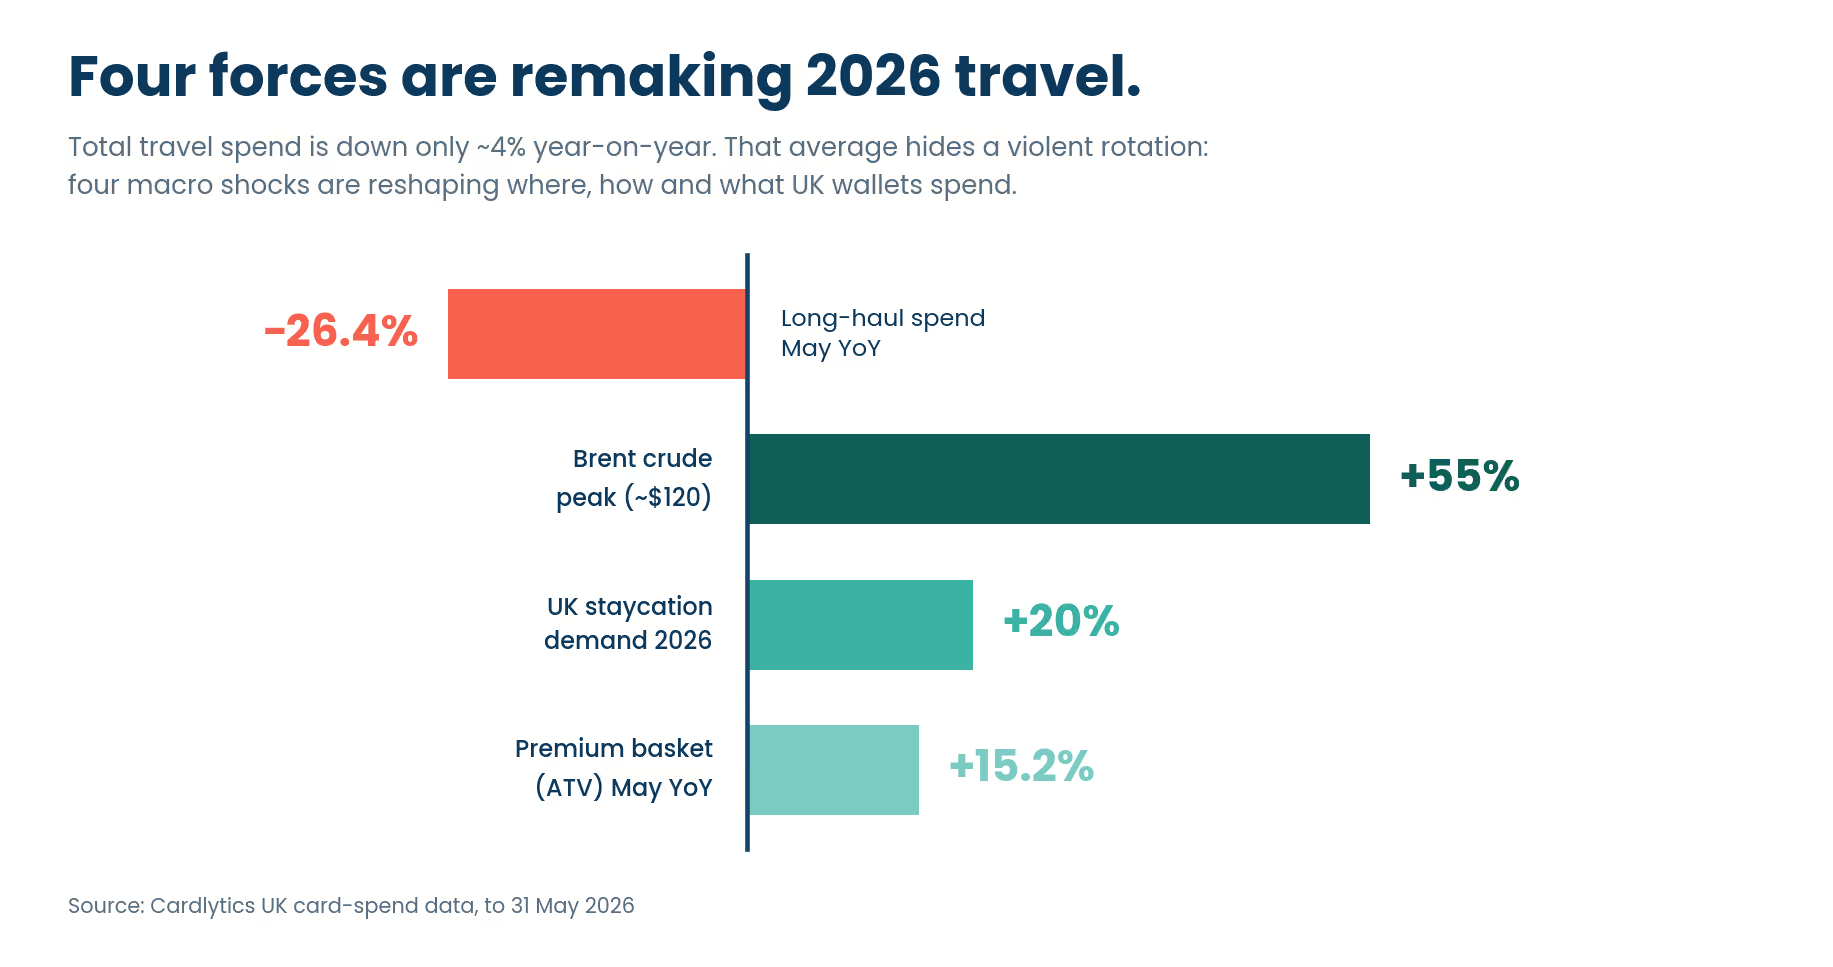
UK travel spend looks steady on the surface — down just ~4% year-on-year. Look closer, and the story isn't decline. It's rotation.
New analysis from Cardlytics, drawing on UK card-spend data to the end of May 2026, shows four macro shocks — the US–Iran conflict, a jet-fuel supply squeeze, a staycation surge, and a resilient premium wallet — quietly redrawing where, how and what UK travellers book.
Four shifts travel leaders shouldn't ignore
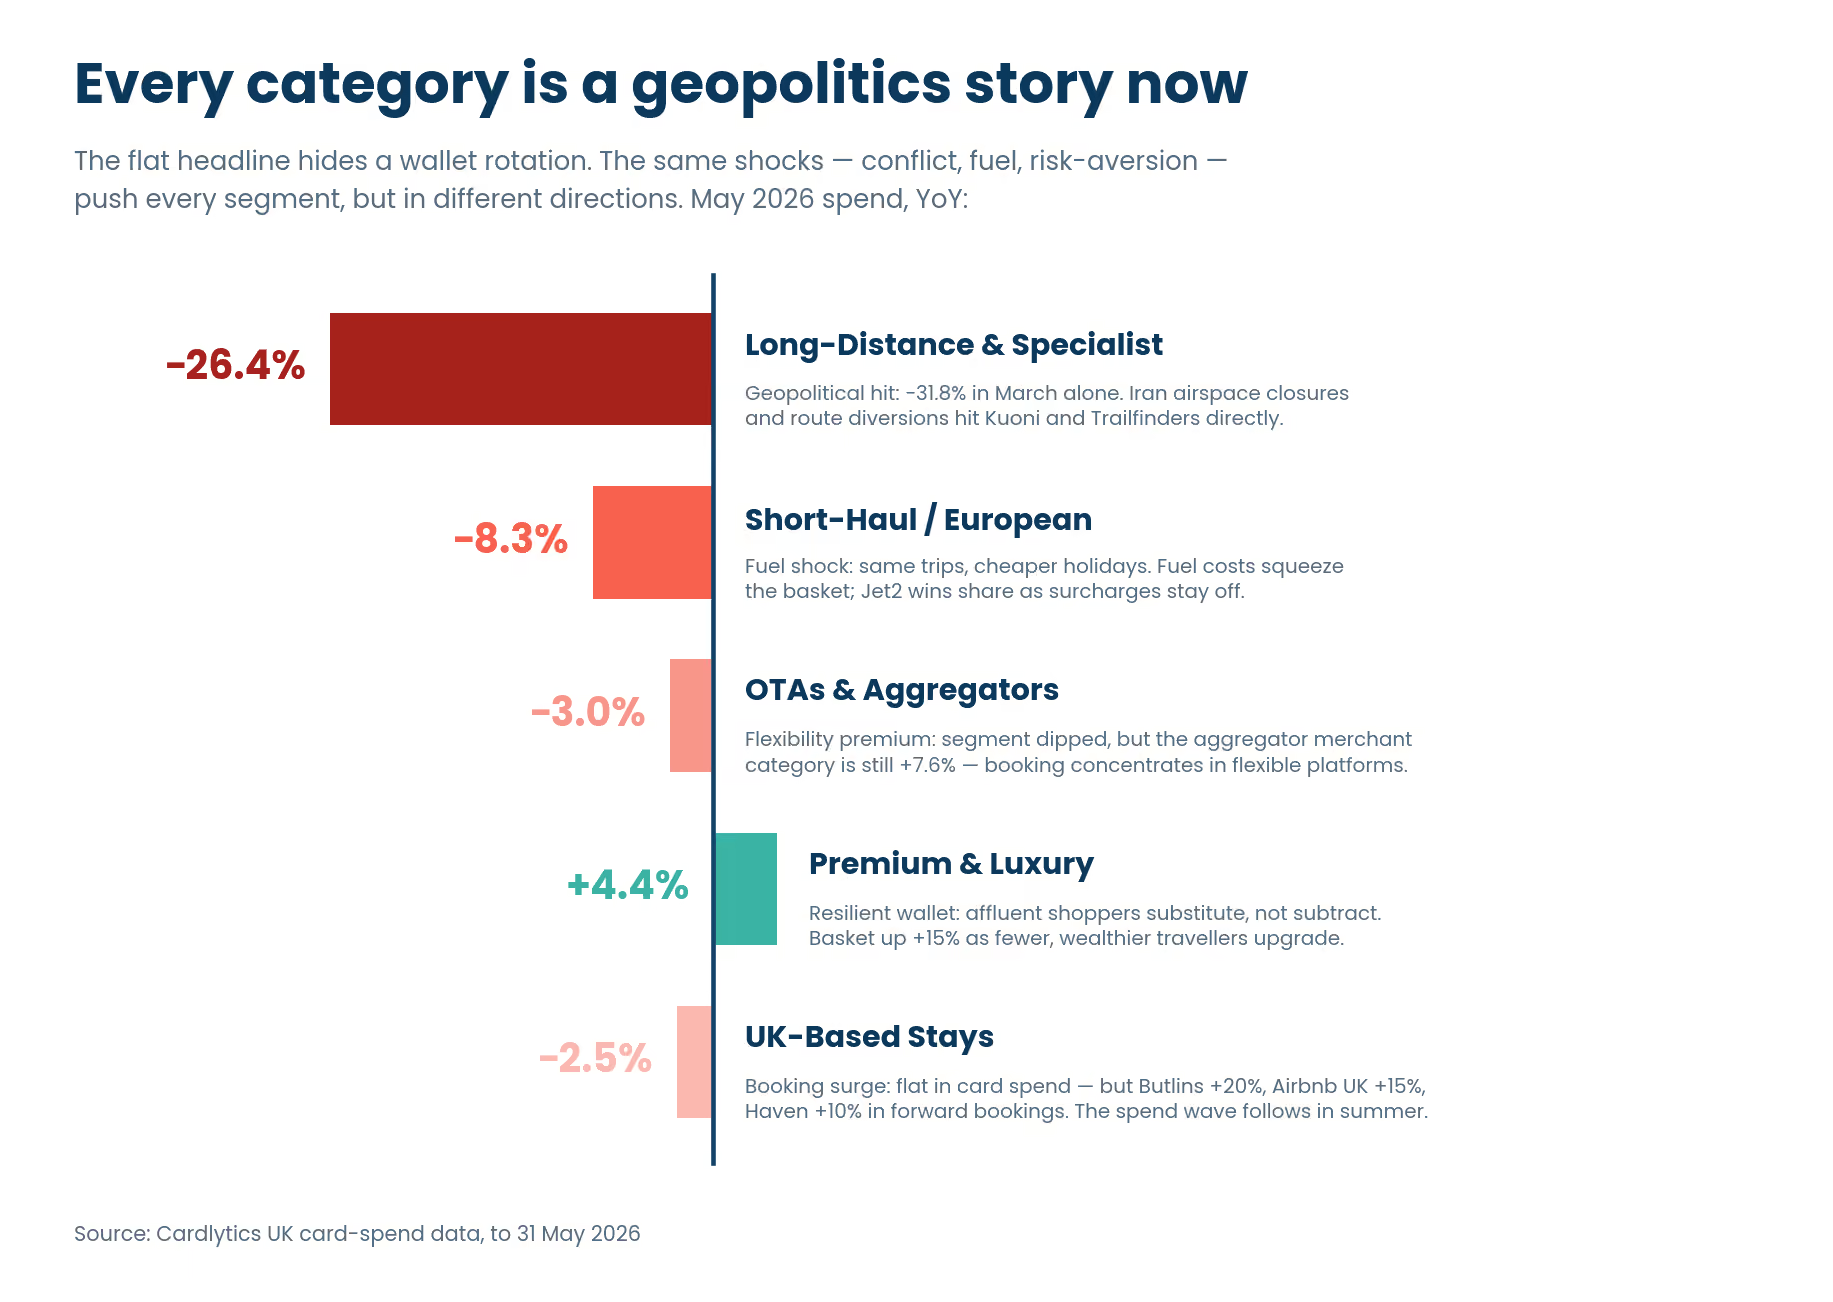
Long-haul is falling off a cliff. Long-Distance & Specialist spend fell 26.4% in May year-on-year — but trips fell 29.4%. Nearly a third of journeys are gone, and rising ticket values are masking a real, geopolitically-driven pullback.
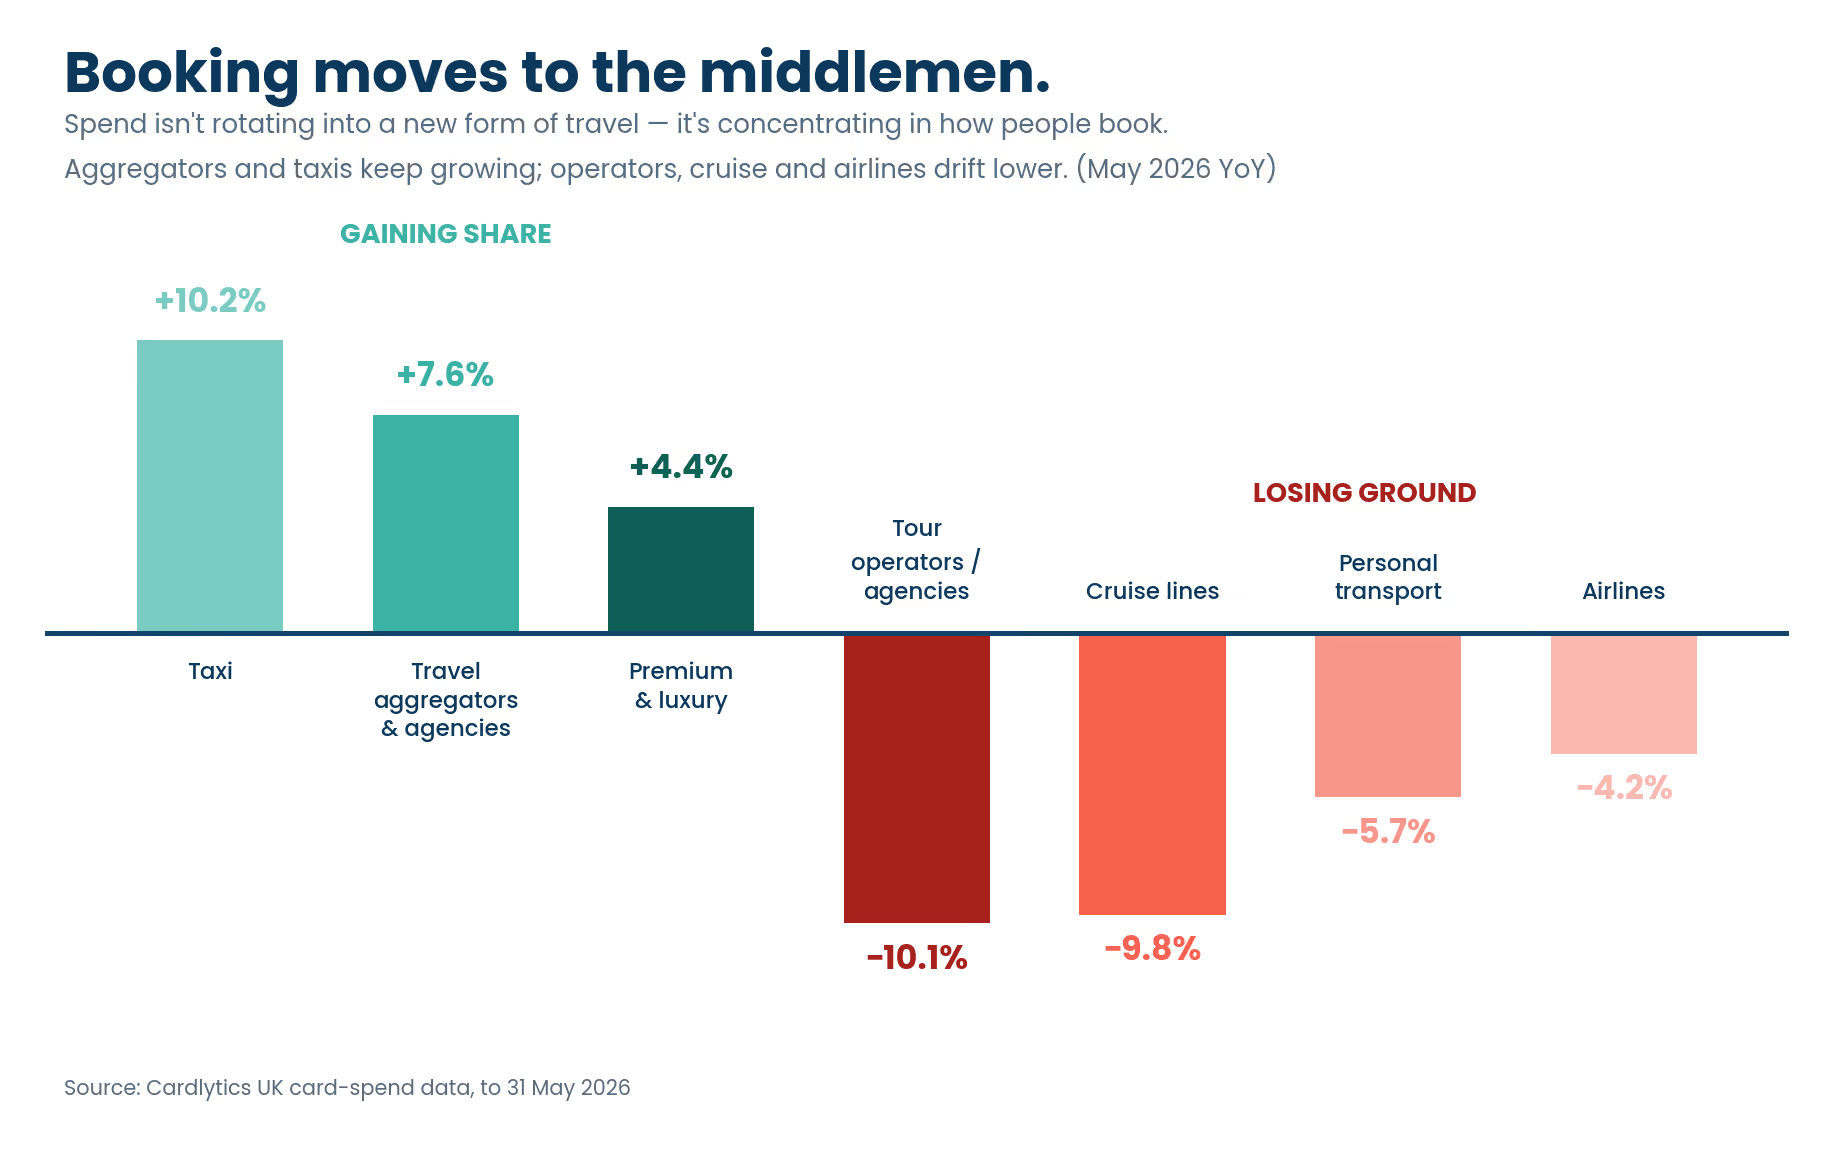
Booking is moving to the middlemen. The travel aggregators and agencies category grew 7.6% while tour operators fell 10.1% and cruise lines 9.8%. Facing an uncertain
backdrop, consumers are paying a premium for flexibility — booking through platforms they trust to find value and re-route them.
Premium travellers substitute — they don't subtract. Premium & Luxury spend rose 4.4%, with the average basket up 15.2%. Fewer, wealthier travellers are trading up, and luxury domestic stays are absorbing displaced long-haul demand.
The staycation wave hasn't hit the card data yet. UK domestic demand is up around 20% year-on-year, with 46% of Brits citing global conflict as a reason to holiday at home. Forward bookings are surging — the spend wave lands this summer.
Unlock the full State of Spend: Travel Edition
The headline numbers hide the real story: a collapse in long-haul trips, a flight to flexible booking, and a premium wallet that refuses to slow down. Download the full report for the segment-by-segment breakdown and four travel plays for a cautious wallet.
Inside the report:
- The Long-Haul Cliff: why trips fell nearly 40% in March — and what rising
ticket values are hiding. - Same Shift, Five Behaviours: spend decomposed into trips and basket size, from mass desertion to trading up.
- Where Spend Flows: the merchant categories gaining and losing share as booking concentrates with aggregators
- Four Travel Plays: where Card-Linked Offers and Cardlytics Insights should focus for OTAs, long-haul operators, premium brands and short-haul carriers.
The UK State of Spend: Who's Winning or Losing in H1 2026
Four signals from a shifting wallet — and what they mean for advertisers.
UK consumer spending looks healthy on the surface. Look closer, and the wallet is quietly diverging.
New analysis from Cardlytics, drawing on UK purchase data across more than 60 million enabled accounts, shows positive year-on-year spend growth across every macro category in H1 2026. But transactions, customer counts, and basket sizes tell a very different story underneath.
Consumers are protecting holidays, paying more for fewer nights out, and trading down on the high street.
Three shifts leaders shouldn't ignore
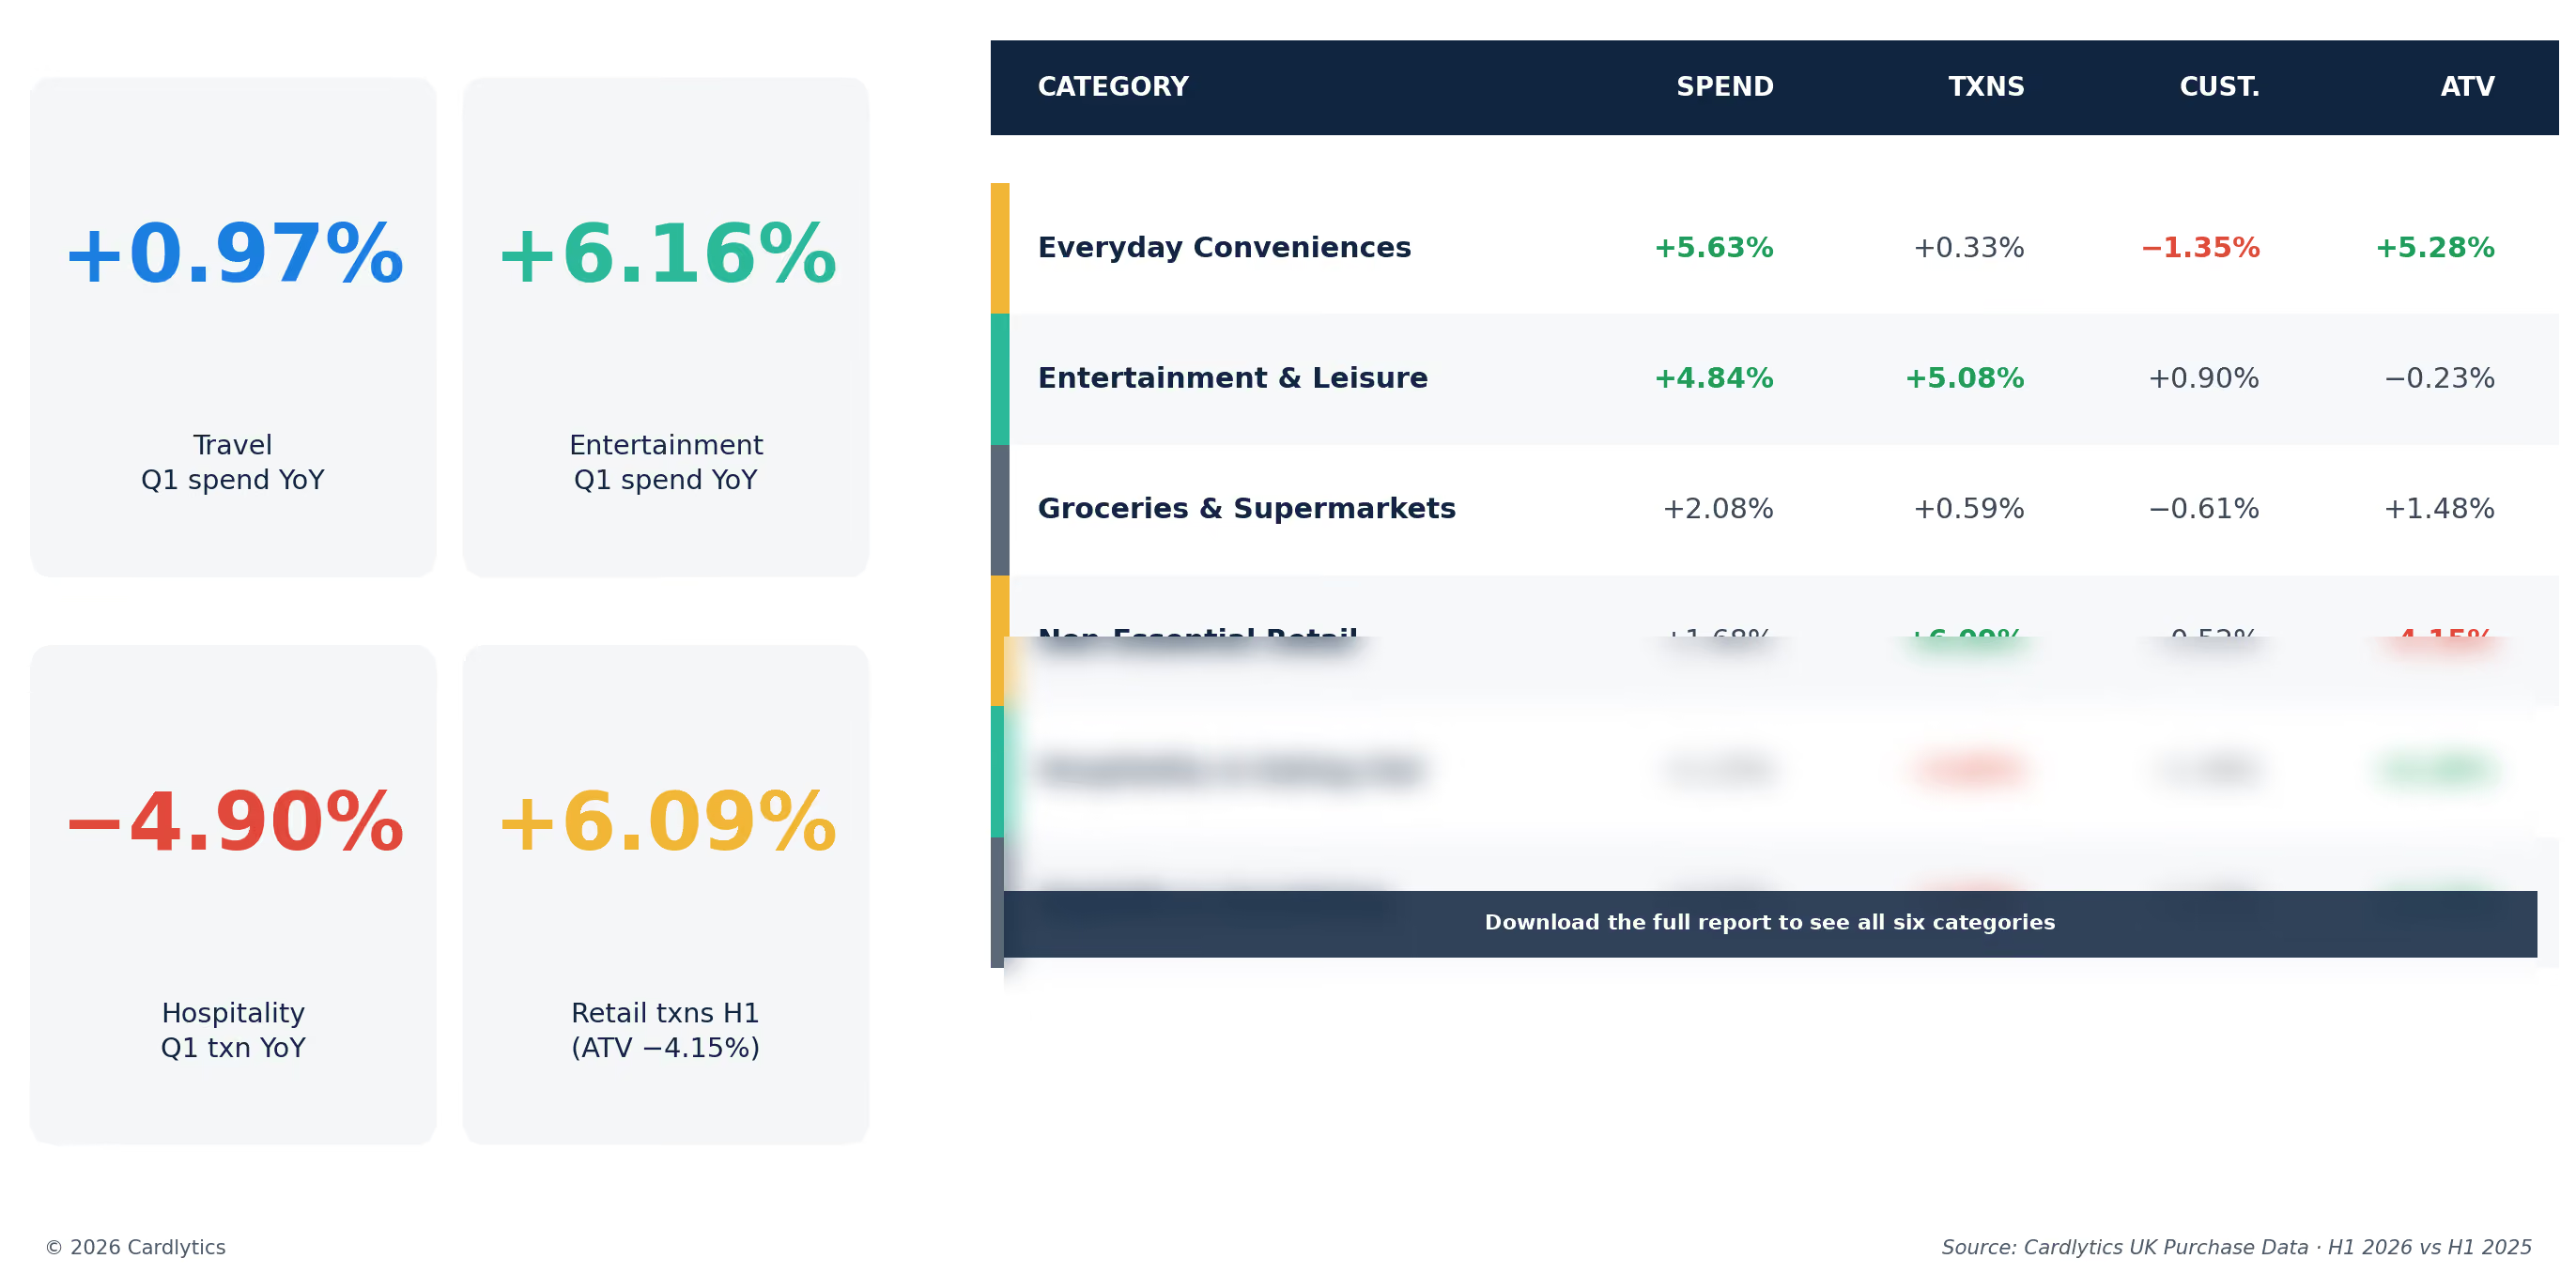
Holidays held, but restaurants didn't. Hospitality lost 3.83% of transactions year-on-year in H1; Nightlife lost 3.95%. Travel grew 0.97% in Q1, with Entertainment & Leisure up 6.16%.
Inflation is doing the heavy lifting on the high street. Hospitality, Nightlife, and Everyday Conveniences all posted positive spend growth — but only because average ticket value rose around 5%. Real visit frequency is falling.
Retail is winning volume and losing value. Non-Essential Retail transactions rose 6.09% in H1 while average basket size fell 4.15%. Consumers are shopping more often and spending less per basket — a clear discount-led signal.
Spend and transactions tell two different stores
Unlock the full Q2 State of Spend report
Top-line growth is masking a structural pullback in mid-week dining, a narrowing active customer base, and a discount-driven retail shift. Download the full report for the category-by-category breakdown and the four advertiser playbooks for an uneven wallet.
Inside the report:
- The "Who Is Losing?" Index: How six macro categories really performed once ATV inflation is stripped out.
- The Hospitality & Nightlife Squeeze: Why footfall is down ~4% even as spend ticks up.
- The Retail Paradox: Record transaction frequency colliding with shrinking baskets.
Four Playbooks for Advertisers: Where to drive frequency, where to grow basket size, and where loyalty beats acquisition in Q3.
Cardlytics Banking Loyalty Index 2026
From loyalty to relevance: Why personalised rewards matter more than ever for UK banks
UK consumers may feel loyal to their bank, but that loyalty is increasingly conditional.
New research from Cardlytics, based on a nationally representative survey of 4,000 UK adults, shows that while most customers are not actively planning to switch, many are open to reassessing where they bank when the value is clear.
Two thirds of consumers (65%) say they feel loyal to their main bank, and 60% say they are unlikely to switch in the next 12 months. But that stability should not be mistaken for permanence. More than half (57%) have switched their main bank account at some point as an adult, and many now spread their money across more than one provider.
The result is a banking market where retention is no longer just about keeping customers from leaving altogether. It is about staying relevant in more of their everyday financial decisions.
Trust and service still matter, but they are now the baseline
When asked what keeps them with their current bank, UK consumers are most likely to cite good customer service (40%), brand trust and reputation (35%), and the quality of mobile or online banking (32%).
These are the foundations of a strong banking relationship. They help explain why customers stay put, particularly older generations. For example, Baby Boomers are significantly more likely to say customer service is a key reason they stay with their bank (50%).
But these factors are increasingly expected. They are essential to retention, but on their own they may be less effective at creating real competitive advantage.
Unlock the full Cardlytics Banking Index 2026
The shift from passive loyalty to active relevance is changing how the UK banks. To read the full analysis on how financial value triggers action, the impact of personalised rewards on 18 to 34 year olds, and why loyalty is no longer exclusive, download the complete report below.
Get the full insights to discover:
- The Switching Triggers: The specific financial incentives driving 25% of Gen Z to reconsider their bank.
- The Personalisation Opportunity: How tailored rewards can increase retention by up to 55% for key demographics.
- The Visibility Challenge: Why 22% of customers are unaware of the rewards their banks already offer.
- Multi-banking Trends: Why customers are spreading their finances and how to capture a greater share of wallet.
Where have all the shoppers gone?
Where have all the shoppers gone?
How UK shoppers are narrowing their choices — and what it means for growth
After two years of post-pandemic recalibration, UK consumers are still spending. But they are becoming more selective in where, when and why they do so.
Cardlytics’ latest State of Spend report draws on first-party purchase data from 23 million UK bank customers across the spring and summer period.
What it shows is simple: retail growth remains present, but increasingly uneven. Categories that feel essential, convenient or low-risk continue to attract spend. More discretionary and deferrable purchases are coming under greater pressure.
This is less a story of demand disappearing and more one of decision-making narrowing. For retailers and brands, growth will depend less on broad consumer momentum and more on securing a place in a smaller set of deliberate purchasing moments.
Essentials: fewer trips, tighter control
Essential categories remain the most resilient part of the market. But the pattern of spending suggests households are becoming more deliberate in how they manage everyday needs. Growth is still there — it is just concentrated in channels that offer either convenience at scale or a clearer sense of value.
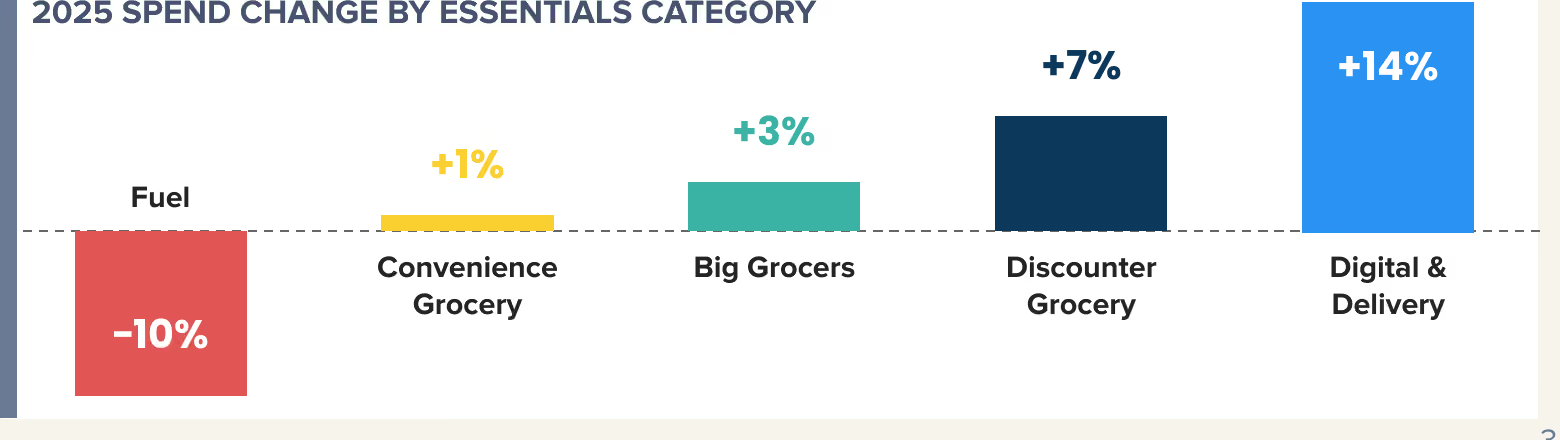
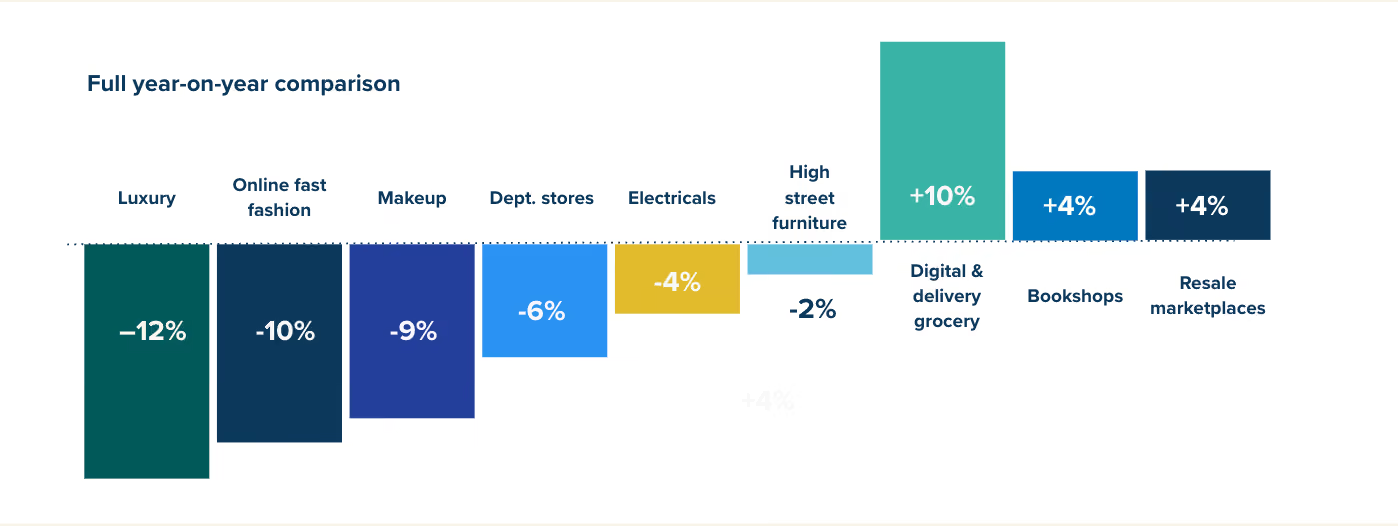
The strongest performance continues to come from Digital & Delivery Grocery, where spend rose 17% in 2024 and 14% in 2025. Transactions also grew strongly, pointing to a channel still benefiting from continued adoption and slightly larger baskets.
Discounter Grocery shows a similar pattern, with spend up 9% in 2024 and 7% in 2025, supported by steady transaction growth. The category continues to act as a dependable value channel for households managing budgets carefully.
Among Big Grocers, growth is more subdued — 6% in 2024, slowing to 3% in 2025 — while transactions moved broadly flat. Spending is being held up by larger baskets rather than more visits. Convenience Grocery has come under greater pressure still, with trips down around 3%.
Fuel is the clearest sign of retrenchment within essentials. Spend declined 5% in 2024 and 10% in 2025, with early 2026 data indicating this behaviour is continuing.
Cardlytics analysis
Essential spend is still being protected, but the shape of that spend is changing. Consumers are concentrating everyday purchasing into channels that help them feel organised or in control — whether that’s delivery-led convenience or discounter-led value.
For marketers, the opportunity is less about generating additional need and more about intercepting planned purchase moments with a clear reason to choose one retailer or brand over another. In a market where fewer shopping occasions carry more weight, securing a greater share of each visit matters more.
Retail: a resilient base, but narrowing engagement
Retail continues to grow — but that growth is becoming more uneven. The strongest performance is increasingly concentrated in categories that feel accessible, repeatable or easy to justify. Traditional and aspirational areas are finding it harder to sustain engagement.
Make-up & Beauty remains one of the clearest areas of resilience. Spend rose 11% in 2024 and 8% in 2025, with transactions also moving in the right direction. It’s one of the few categories where shoppers still see room for smaller, more manageable discretionary purchases.
Online Fast Fashion continues to expand, up 14% and 9% across the two years, though baskets have softened slightly — shoppers engaging more frequently but with tighter control on basket size. Marketplaces are another strong area of growth, reinforcing their role as a flexible, value-conscious route to purchase.
Elsewhere, the picture tightens. High Street Fashion growth has slowed and transactions have flattened. Department Stores saw spend fall 3% in 2024 and 4% in 2025, pointing to an ongoing footfall challenge. And Luxury / Designer Fashion spend declined 6% in 2024 and 8% in 2025 — purchases are still happening, but among fewer shoppers, less often.
Cardlytics analysis
The categories still growing are not necessarily those with the strongest brand pull. They are the ones most aligned with how consumers want to shop now: flexibly, frequently and with lower perceived risk.
For brands, that raises the importance of relevance, value communication and mission-based targeting over broader assumptions about seasonal demand. In a more selective market, success will depend less on broad visibility alone and more on giving shoppers a clear, immediate reason to engage.
Household: from upgrade to upkeep
Across home-related categories, the shift from 2024 into 2025 points to a more cautious consumer mindset. Spending hasn’t disappeared — but households are more willing to maintain and replace than to embark on larger, more discretionary home purchases.
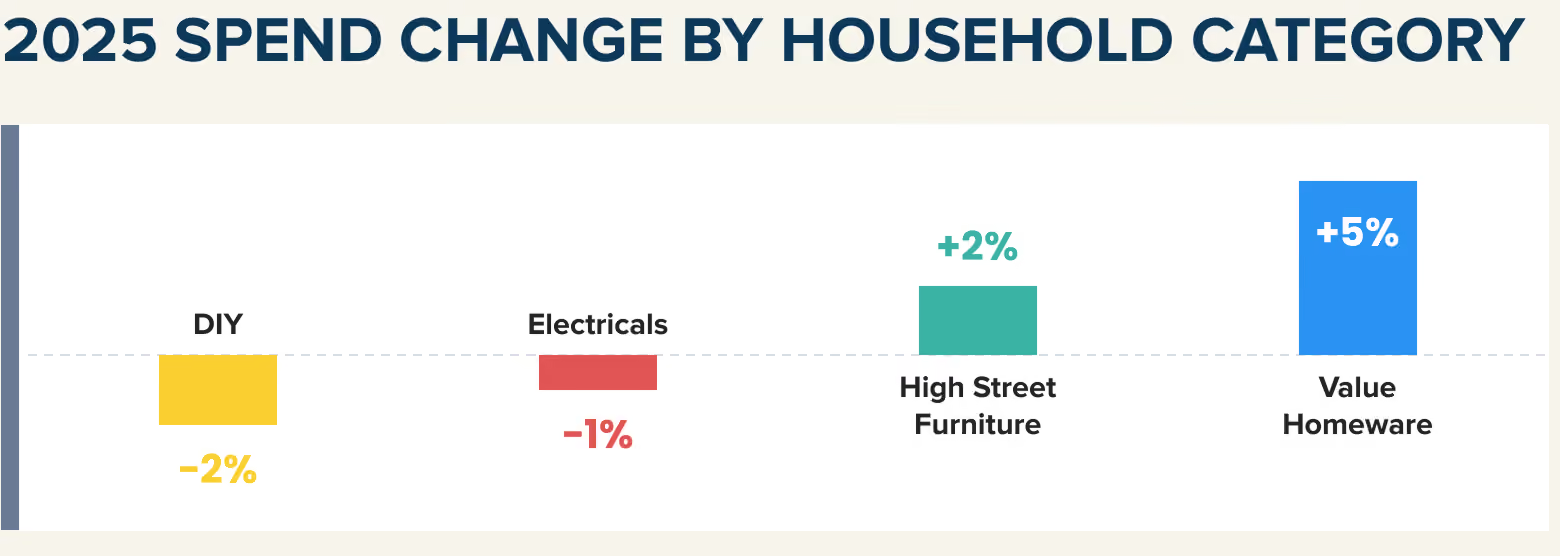
Value Homeware has remained relatively stable, up 9% in 2024 and 5% in 2025. High Street Furniture shows a clearer slowdown, moving from 6% growth to 2%, with spend concentrating in fewer, higher-value occasions.
The pattern is more pressured in DIY. After 3% growth in 2024, spend moved into a 2% decline in 2025, with transactions down around 5%. Electricals follow a similar trajectory — from 4% growth to a 1% decline — with purchases increasingly concentrated in fewer, more considered buying moments.
Cardlytics analysis
In home-related categories, demand increasingly looks tied to maintenance, replacement and justified necessity rather than inspiration or upgrade. That changes what effective messaging looks like.
Brands here may need to focus less on aspiration and more on practicality, durability and timely relevance if they want to convert consumers who are clearly weighing whether a purchase can wait. The strongest opportunities come from moments where need is immediate and the value exchange is clear.
Wider discretionary: where the drop-off is most visible
The clearest signs of pressure appear outside the core retail categories — in areas where spending is most optional and easiest to postpone. Here the challenge is not how much consumers spend when they engage, but whether they enter the category at all.
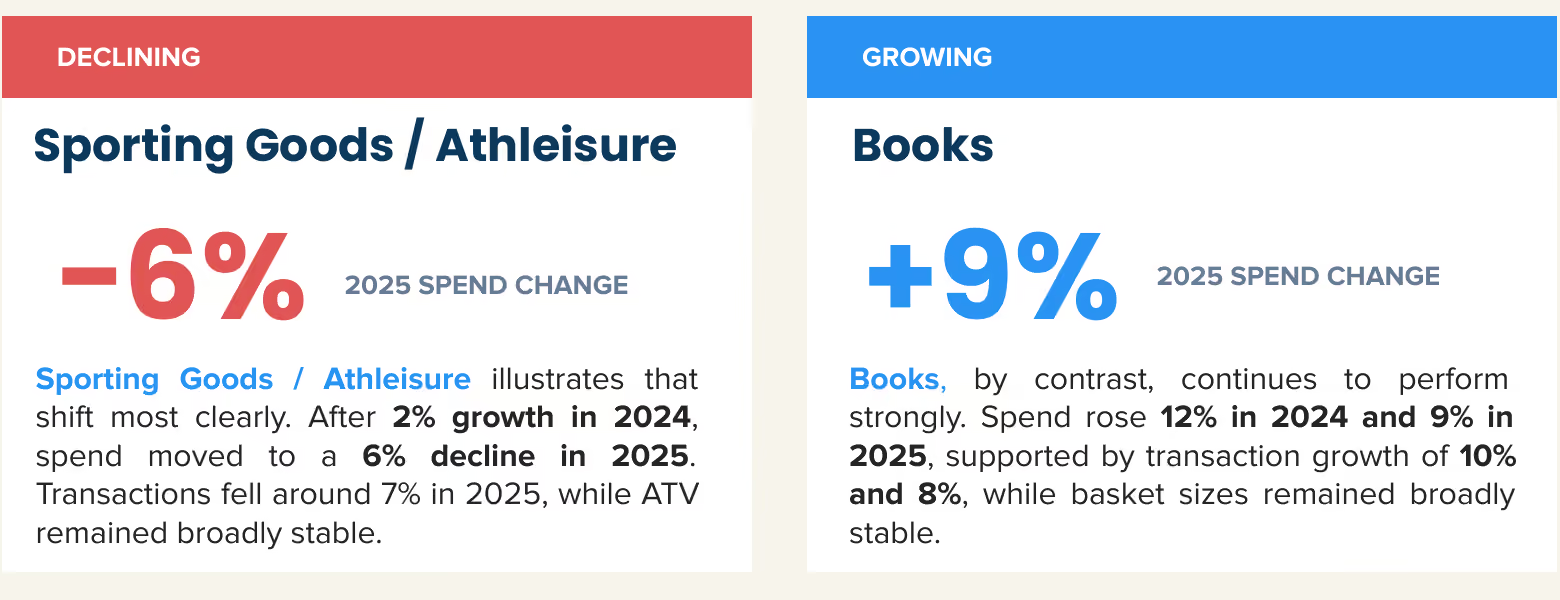
Sporting Goods / Athleisure illustrates the shift most clearly. After 2% growth in 2024, spend moved to a 6% decline in 2025, with transactions down around 7% while ATV stayed broadly stable. The pressure is being driven by fewer shoppers choosing to participate — not by smaller baskets.
Books, by contrast, continues to perform strongly, up 12% in 2024 and 9% in 2025. It remains one of the clearest examples of a discretionary category where engagement holds up — consumers are still willing to spend where purchases feel lower-cost, familiar or easy to justify.
The issue is no longer simply whether shoppers can spend, but which categories still make the cut.
Cardlytics analysis
For discretionary categories, the core challenge is re-engagement. When consumers are reducing the number of optional purchases they make, brands need stronger triggers to prompt participation in the first place.
That may mean leaning harder into immediacy, occasion-based relevance, perceived value or more functional reasons to buy — rather than assuming promotions alone will unlock demand. Growth depends less on broad category momentum and more on giving consumers a compelling reason to opt in at all.
Looking ahead into 2026
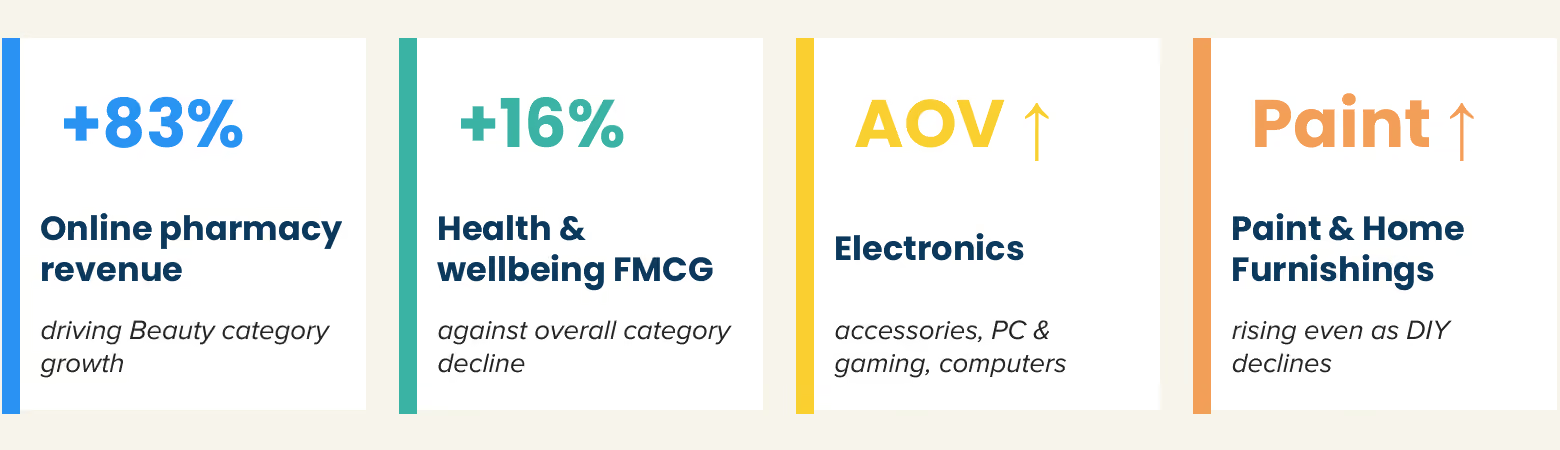
Early 2026 performance is already pointing to where the narrowing of shopper demand is concentrating. Online pharmacy revenue is driving Beauty category growth. Health & wellbeing FMCG is up against overall category decline. Electronics AOV is rising on accessories, PC and gaming. And Paint & Home Furnishings are rising even as DIY declines — a clear signal that the channel and use-case shifts identified in this report are continuing.
Fewer decisions, higher stakes
The summer shopper has not disappeared, but the number of decisions they appear willing to make has narrowed.
Across the market, the strongest performance is coming from categories that feel essential, convenient or easy to justify, while more deferrable and aspirational purchases are facing greater pressure. That does not point to a collapse in consumer demand — it points to a consumer mindset that is becoming more selective about where spending feels worthwhile.
For retailers and brands, that creates a more competitive environment. Growth is no longer just about being present at the point of purchase — it is about being relevant enough to be included in a smaller set of deliberate decisions. In that context, value, timing and clarity matter more, particularly in categories where engagement can no longer be taken for granted.
How marketers should show up
01. Protect existing shoppers first
Shoppers don’t leave in one move — they drift. Transaction data already shows who’s slipping. Reaching a lapsed shopper around their next likely need window is cheaper than finding a replacement, and more effective than broad re-acquisition.
02. Growth sits in small, repeat purchases
The categories still expanding are the ones where the purchase feels small, familiar and easy to justify. Find the version of your product that fits a smaller, more frequent moment — something a shopper says yes to without deliberation.
03. Solve for participation, not basket size
The harder question isn’t what a shopper spends when they show up — it’s whether they show up at all. Discounting rarely pulls someone into a category they’ve stepped out of. An immediate, tangible need does.
The brands best placed to outperform will be those that understand which purchase moments consumers still prioritise — and can show up in those moments with a clear and compelling reason to buy.
Talk to Cardlytics about how purchase intelligence and card-linked offers can help your brand secure a place in a smaller, more deliberate set of consumer decisions — www.cardlytics.com
Q1 2026 State of Spend: The controlled consumer
The Controlled Consumer:
Why UK shoppers entered 2026 already spending with intent
The New Year value hunt started before Christmas.
Cardlytics’ State of Spend analysis of Q4 2025 and early Q1 2026 shows that UK consumers did not loosen their spending habits over the festive period. Instead, they became more deliberate about how and where they spent. Drawing on card-based transaction data from over 23 million bank accounts, the analysis points to a shift toward a more controlled approach to spending that is now shaping behaviour into 2026.
The last State of Spend showed that UK consumers had returned to the market, but with conditions. Spending resumed, but cautiously. Shoppers scrutinised price, convenience and perceived quality, pulling back when expectations were not met. Consumers would still spend, but largely when prompted by the right offer or moment.
The latest data shows that this scrutiny has since become embedded in shoppers’ habits. December revealed how consumers were already operating under tighter decision-making rules as they approached the new year.
With inflation ticking up again at the end of the year, cost pressures remained firmly in place. Rather than retreating from spending altogether, consumers adapted — switching formats, trading down and filtering purchases more aggressively. Festive spending held, but it was more controlled, with loyalty weakening and defaults increasingly questioned. As a result, consumers entered Q1 already spending more selectively.
Read the full report by downloading it here.
The Golden Quarter is Changing: Inside the 2025 State of Spend
The Golden Quarter is Changing: Inside the 2025 State of Spend
The UK’s peak retail season is evolving. Consumers are still spending, but they’re more selective, strategic, and values-driven than ever before. Based on spend data from over 23 million UK bank accounts and nationally representative research, Cardlytics' State of Spend report uncovers what’s shaping the 2025 Golden Quarter — and where brands should focus to win.
Headline Trend Summaries (With Light Stats)
1. Black Friday is no longer the main event
The era of single-day shopping spikes is fading. Our data reveals that consumers are spreading spend across weekends and early December instead. Brands focused only on the Friday are missing the bigger picture.
2. Gifts that matter and don’t just impress
Over half of consumers say they’re choosing meaningful or practical gifts this year. Beauty and books are holding strong, while luxury and electrical categories are losing ground.
3. Fashion is fragmenting
Fast fashion still performs, but growth is slowing. Shoppers are shifting toward resale platforms and marketplaces that offer affordability and sustainability in one.
4. Grocery is about confidence, not just cost
Spend is still rising across grocery - but discounters, delivery services, and high-end grocers are outpacing traditional supermarkets. Value is no longer just about price; it’s about trust and convenience.
Consumers are still buying. They’re just doing it on their terms. The winners in 2025 will meet them where they are — with relevance, value, and visibility.”
Want the full data?
The full report includes:
- Category-by-category breakdowns from 2022 to 2024
- 2025 retail forecasts across 14 key sectors
- Consumer behaviour insights and shopping intent
- Strategic recommendations for campaign planning
Download the Full Report
UK Loyalty Movement Report: Retail
UK Loyalty Movement Report: Retail
Introduction
In our previous report, Redefining Customer Loyalty, Cardlytics defined loyalty as a consumer’s preference for a merchant over its competitors, analysing spending across six industries to measure customer loyalty and spending patterns with both loyal and non-loyal customers.
But customer behavior isn’t fixed - customers shift between loyalty segments over time. Understanding these shifts helps identify churn and informs strategies to nurture relationships and move customers to higher loyalty segments. In our UK Loyalty Movement Report, we dive into customer behavior in the Retail category to better understand engagement over time by analyzing more than £245 billion in consumer spend behavior.*
Retail Category Loyal Customers
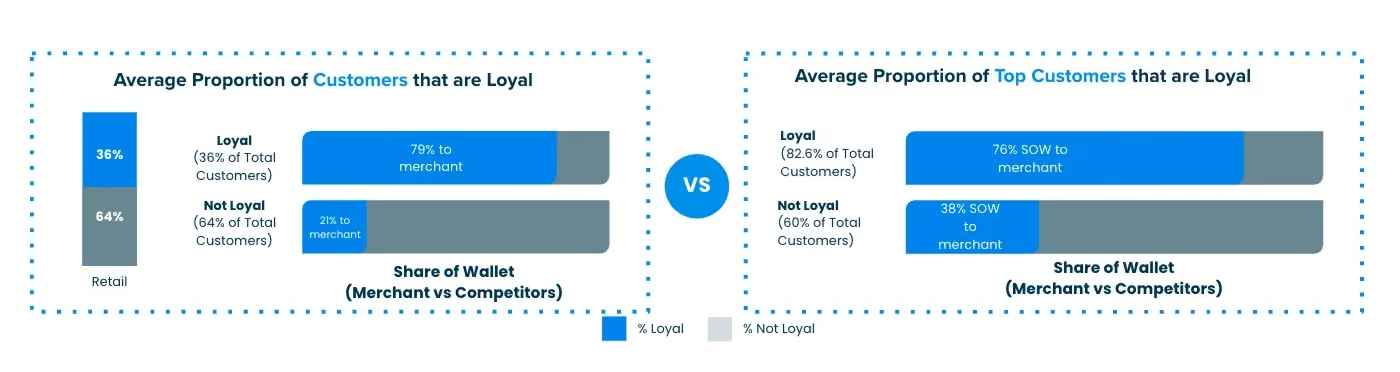
On average, 64% of a merchant’s customers are not actually loyal. But the loyal segment has a much higher share of wallet (79%) than a not loyal segment (21%).
Top Customers (top 20% of most frequent transactors) show a strong uptick as loyal vs not loyal customers. But the loyal customer segment shows more than 3x higher share of wallet.
Findings
We looked into purchase data across Retail in the UK over the last 8 quarters (Q1-23 through Q4-24) on a quarter by quarter basis to see whether even the “most loyal” customers showed changes in their purchase behavior.
Retail Loyalty Movement
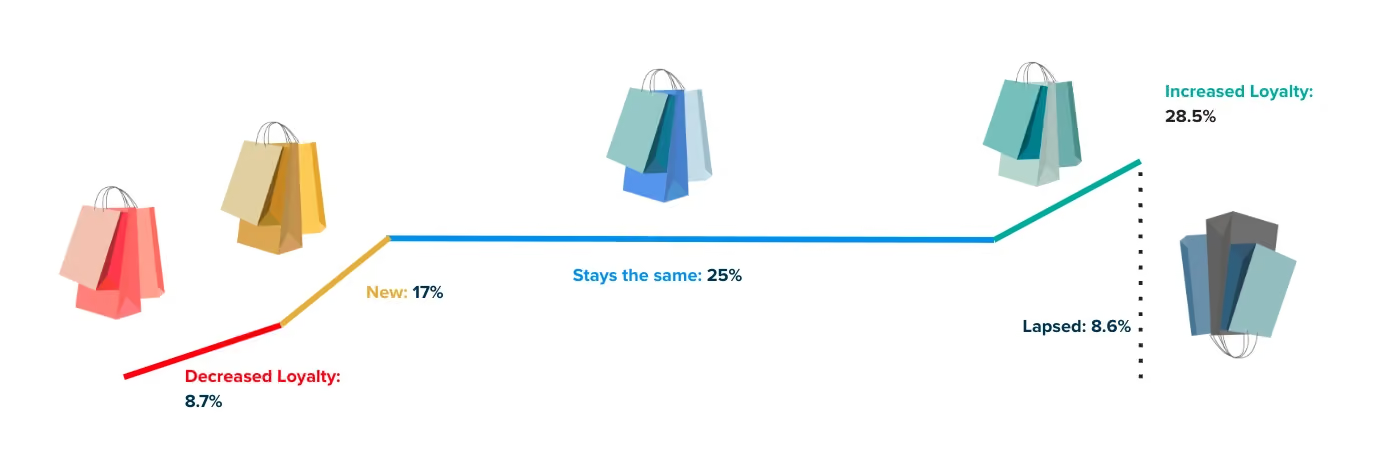
Overall, quarter over quarter, 25% of customers tend to remain in their existing segments while 37.2% increase or decrease their loyalty to a merchant. Yet there is much more extensive customer loyalty movement within the “not loyal” segments.
Segment movement
The Tied segment (part of the Not Loyal group) demonstrates the most volatility — with just 7% remaining stable and 29% moving up and 29% moving down into other segments.
Retail Leaky Bucket
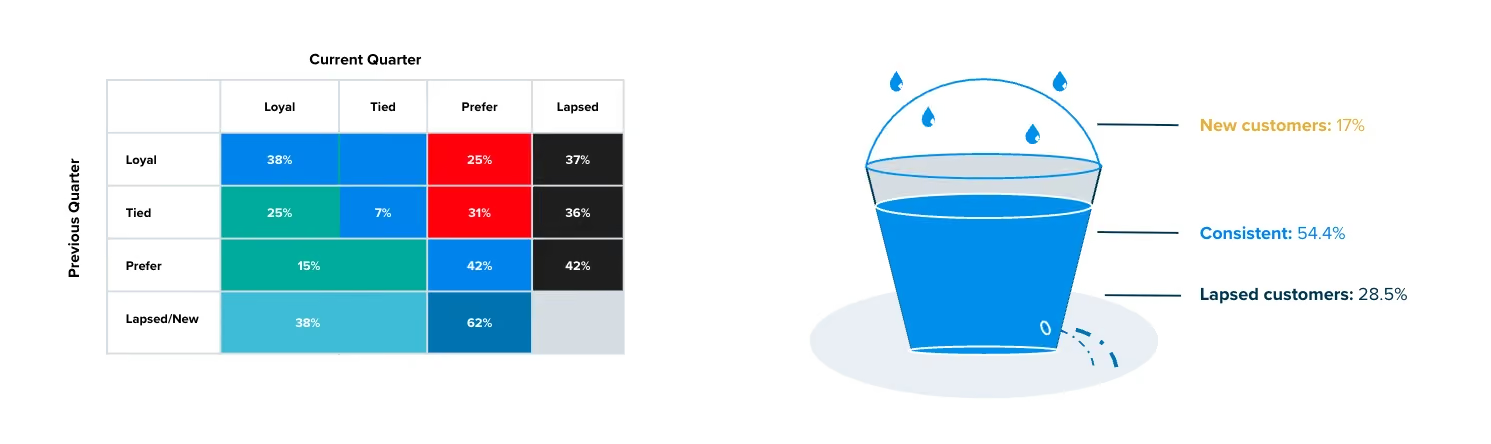
Retail brands are acquiring new customers yet even more existing customers are moving into the lapsed tier. This cycle can be reversed by continuing to nurture existing customers.
Diving deeper into the individual segments tells us:
- Loyal customers and those that Prefer the competition are the most stable segments, with 38% and 42% respectively staying in the same category from one
quarter to the next. This indicates a strong commitment to brand preference — whether for your brand or a competitor's. - Customers in the Tied segment exhibit the highest level of movement, with just 7% remaining Tied quarter-over-quarter. These shoppers are the most susceptible to influence and represent a key opportunity for brands aiming to tip the scales in their favour.
- Interestingly, Loyal customers still show a 25% lapsed rate, which is comparable to the Tied segment’s 36% lapsed rate. This suggests that attrition among Loyal customers may not be driven by brand disengagement, but rather by natural gaps in purchase cycles — for example, customers who buy apparel less frequently.
Definitions of Customer Segments
Loyal Customers:
- Loyal: Only shop with a specific brand, or have the highest share of wallet with a given brand and relative rank is lower than all other brands in consideration set
Not Loyal Customers:
- Tied: Similar relative ranks to 2 or more brands regardless of share of wallet ranking
- Prefer: Lower share of wallet and higher rank than other brands in their consideration set
- Lapsed: Shopped historically but do not shop currently, as defined by the analysis time period
- New: Shop currently but have not shopped historically, as defined by the analysis time period
Takeaways
Marketers know it’s more costly to acquire or re-acquire customers than to keep existing ones engaged. When brands neglect current customers, they risk losing them and undoing past investment yet the reasons why a customer might “lapse” is different depending upon their loyalty tier. Loyalty is fragile and demands ongoing effort as competition is always close by. To stay top of mind, marketers must continuously nurture relationships, understand customer needs, and offer seamless experiences. To foster loyalty with your customers, consider these recommendations:
- Use an “always on” strategy to keep customers engaged, regardless of purchase
frequency. - Regularly update/refine customer segments and adjust reward offers to keep
them engaged. - Use targeted campaigns to boost loyalty and revenue.
Cardlytics can deliver a comprehensive Customer Loyalty Analysis with insights into customer behavior and movement across defined loyalty segments. Contact us for more details.
* For this report, we've selected the entire retail category in our data, collectively representing over £245bn in annual card spend. This sample differs from the previous Customer Loyalty Analysis report.
Get our insights delivered to you
Stay up to date. Subscribe now.